White paper 06 · Chapter 6
Green iron: a long-term option for Central Africa, gated by ore, power and gas
The deepest cuts in steel’s emissions will come from making iron without coal: first with natural gas in direct-reduction shaft furnaces, then with an increasing share of hydrogen made from low-carbon electricity. Regions that combine iron ore with abundant clean energy could make that iron and ship it as hot-briquetted iron (HBI) to steelmakers elsewhere. Central Africa has ore and large undeveloped hydropower. It does not yet have the DR-grade concentrate, the contracted gas or the low-cost firm electricity that green iron requires. For RC-1, green iron is therefore a reserved option, to be earned step by step, not a near-term product.
In this chapter (8)
- 6.1 Why ironmaking is where the carbon is
- 6.2 Gas first, then hydrogen
- 6.3 The ore-quality question
- 6.4 Africa’s direct-reduced iron is a North African story so far
- 6.5 What the studies say about Africa’s green-iron opportunity
- 6.6 How much power would hydrogen need in Cameroon?
- 6.7 Gas: the bridge whose availability has just changed
- 6.8 A stepwise, gated route
6.1 Why ironmaking is where the carbon is
In the blast-furnace route, almost all of steel’s CO2 comes from turning ore into iron; converting iron into steel and rolling it add comparatively little. In an electric works that buys DRI, the same carbon appears upstream, in the supplier’s shaft furnace. Chapter 4 showed that the imported iron units are the largest block in RC-1’s footprint. Lowering the carbon content of iron, wherever it is made, is therefore the central task of steel decarbonisation.
Two technologies dominate the pipeline. Gas-based direct reduction, using the MIDREX or Energiron processes, already produces about two-thirds of the world’s DRI; the rest is made mostly in coal-fired rotary kilns in India [S13]. The same shaft furnaces can be designed to run on a rising share of hydrogen, up to 100%, because the reducing gas they use from natural gas is already a mixture of hydrogen and carbon monoxide [S15][S17]. Hydrogen reduces iron oxide to iron and water vapour instead of CO2.
6.2 Gas first, then hydrogen
Figure 6.1 places published intensities for ore-based routes on one scale. The worldsteel average for gas-based DRI-EAF is 1.47 t CO2 per tonne [S01]. Energiron reports that its process with natural gas emits about 53% less than the blast-furnace route and, with 100% hydrogen, about 86% less [S15]; applied to the worldsteel blast-furnace average, those percentages correspond to about 1.10 t and 0.33 t per tonne (derived). The Saarstahl and Dillinger project in Germany expects its gas-based DRI-EAF route to emit 1.098 t CO2e per tonne and, with green hydrogen and green power, 0.339 t [S18].
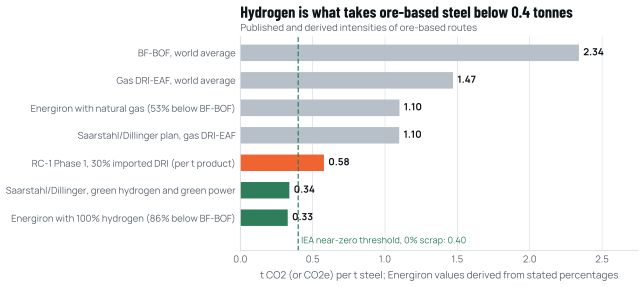
Source: worldsteel [S01]; EC Innovation Centre for Industrial Transformation, Energiron and POWER4STEEL pages [S15][S18]; IEA near-zero threshold [S06]; WP06 model [S90]. Energiron values derived by applying the stated percentages to the worldsteel blast-furnace average.
The energy and material requirements are well documented:
- Natural gas. A modern shaft furnace uses about 9.2 to 10 GJ of natural gas per tonne of DRI; Egypt’s Suez Steel reported a sustained 9.2 GJ per tonne in 2026 [S16][S15]. A 1 Mt/yr DRI module would therefore need about 9.2 to 10 PJ of gas a year, about 11% to 12% of Cameroon’s 2025 gas production of 75.5 billion cubic feet (derived) [S83].
- Hydrogen. Full hydrogen reduction needs about 54 kg of hydrogen per tonne of DRI [S17]. At electrolyser efficiencies of about 45 to 52 MWh per tonne of hydrogen [S05], that is about 2.4 to 2.8 MWh of electricity per tonne of DRI for the hydrogen alone (derived).
- Ore. Both gas and hydrogen shaft furnaces need DR-grade pellets: high in iron and low in silica and alumina, because unlike a blast furnace the shaft furnace does not remove gangue as slag before melting; the gangue goes into the electric furnace and raises its energy use and slag volume.
The cost of the hydrogen route depends above all on electricity. The IEA estimates that hydrogen-based DRI needs power below about US$35 per MWh to compete with gas-based DRI fitted with carbon capture [S05]. The Energy Transitions Commission’s earlier analysis found that electricity below about US$40 per MWh is needed for hydrogen-based DRI to beat carbon capture on a new blast furnace, and that full decarbonisation of steel costs about US$60 per tonne of CO2, or about US$115 per tonne of steel, falling to about US$25 per tonne of CO2 and US$50 per tonne of steel where very cheap renewable electricity is available [S09].
6.3 The ore-quality question
DR-grade iron ore is scarce. The Institute for Energy Economics and Financial Analysis (IEEFA) noted in 2022 that DR-grade ore ideally contains 67% iron or more, and that only about 3% of seaborne iron ore trade had an iron content above 66% [S75]. Agora Industry warned in 2023 that, unless urgent action is taken, demand for DR-grade ore will significantly outstrip supply by 2030 [S11]. IEEFA’s 2026 assessment expects the high-grade market to grow, as new mines and beneficiation plants come on stream [S76], but the scarcity is a structural feature of the transition: the iron ore most of the world mines today was chosen for blast furnaces, which tolerate more gangue.
Cameroon is a significant prospective ore producer. Global Energy Monitor counts 64 Mtpa of iron-ore mine capacity in development in Cameroon, about 9% of the world total [S14]. The Mbalam deposit, whose exploitation permit is held by Cameroon Steel’s sister company Cameroon Mining Company, was reported at the foundation-stone ceremony of the Kribi steel complex as holding more than 2 billion tonnes of ore, including 517 Mt of direct-shipping ore above 62.3% iron [S72]; the reserve statement published under the JORC Code in 2015 gives 62.2% iron for the same 517 Mt (White paper 03, Chapter 4). That is a respectable grade for blast-furnace and sinter feed. It is not DR grade. The much larger lower-grade banded iron formations (itabirites) that make up most of such resources would have to be ground, concentrated and pelletised to reach DR specification.
Table 6.1 Iron-ore quality and the direct-reduction route
| Feed | Typical iron content | Route it suits | What it would take for direct reduction | Source |
|---|---|---|---|---|
| DR-grade pellets | 67% Fe or more, low silica and alumina | Gas or hydrogen shaft furnace | Already DR grade; scarce in seaborne trade | [S75] |
| Seaborne high-grade (above 66% Fe) | above 66% Fe | Shaft furnace after pelletising, or premium blast-furnace feed | About 3% of seaborne trade in 2022 | [S75] |
| Direct-shipping ore reported for Mbalam | above 62.3% Fe as reported; 62.2% in the 2015 JORC reserve statement | Blast furnace, sinter | Not DR grade as mined; would need beneficiation and pelletising | [S72] |
| Itabirite (banded iron formation) | low as mined; upgradeable | After concentration: pellet feed | Grinding, concentration (magnetic or flotation), pelletising; not yet demonstrated at commercial scale in Cameroon | [S72][S75] |
Source: as listed. Concentration processes are generic descriptions, not a project design.
This is the single most important unknown in the green-iron option. If Cameroonian ore can be upgraded economically to DR-grade concentrate and pelletised, the country could one day supply its own steelworks and export iron units with a low carbon content. If it cannot, a Cameroonian direct-reduction module would depend on imported DR-grade pellets, competing for a scarce product. Chapter 10 recommends an early concentrate and pelletising study to settle the question before land, gas or power are committed to the reserve module.
6.4 Africa’s direct-reduced iron is a North African story so far
Africa produced about 16 Mt of DRI in 2025, most of it in North Africa: Algeria 6.70 Mt, Egypt 6.06 Mt and Libya 1.75 Mt on Midrex plant statistics, all gas-based [S13][S03]. On the same statistics Sub-Saharan Africa produced 0.09 Mt, and its gas-based plants, including Nigeria’s 1.02 Mt/yr Delta Steel and South Africa’s 0.80 Mt/yr Saldanha unit, were idle at the end of 2025 [S13]. worldsteel, whose figures include estimates for plants outside that survey, puts output in Uganda, Kenya and Tanzania at about 2.7 Mt [S03]; the two series differ in coverage, and neither shows an operating gas-based plant south of the Sahara. Figure 6.2 shows the contrast.
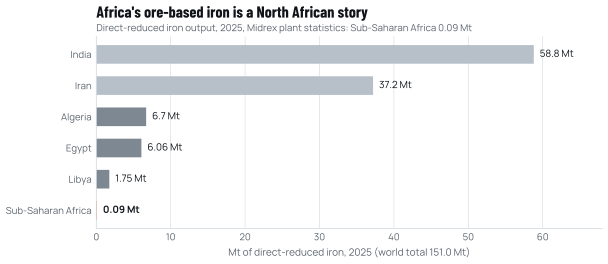
Source: Midrex Technologies, 2025 World Direct Reduction Statistics [S13]; East African estimate from worldsteel, World Steel in Figures 2026 [S03].
The first African green-iron plant is in Namibia. The HyIron Oshivela project, inaugurated in April 2025 with European support, combines solar power, batteries and an electrolyser to make DRI with hydrogen in a pilot of about 15,000 t a year, with plans to scale up in stages [S77][S78]. It is small, but it shows that the technology can be deployed on the continent and that European partners are prepared to co-finance it.
6.5 What the studies say about Africa’s green-iron opportunity
A body of recent analysis argues that ironmaking will partly relocate to places where ore and cheap clean energy coincide. Table 6.2 summarises the studies most relevant to Central Africa.
Table 6.2 Selected studies on green iron and the steel transition
| Study | Main finding relevant to Central Africa | Source |
|---|---|---|
| RMI and Green Hydrogen Catapult, Green Iron Corridors (2024) | Restructuring half of primary steelmaking around green iron could save more than US$25 billion a year across the ten largest importers, about US$80 to US$125 per tonne of steel; fast-tracking corridors could abate about 30 Mt of CO2 a year by 2030; lowest-cost exporters include South Africa and Mauritania | [S10] |
| Agora Industry, 15 Insights on the Global Steel Transformation (2023) | Net-zero steel is feasible by the early 2040s; green iron trade benefits exporters and importers; DR-grade ore demand will outstrip supply by 2030 unless urgent action is taken | [S11] |
| Agora Industry and Cambridge Econometrics, Green Iron, Shared Gains (October 2026) | Green iron trade raises GDP and employment in both exporting and importing countries; South Africa is modelled to gain about 161,000 jobs by 2050 | [S12] |
| Energy Transitions Commission, Mission Possible: steel (2018 to 2019) | Full decarbonisation of steel costs about US$60/t CO2 (about US$115/t steel), falling to about US$25/t CO2 with very cheap clean power; hydrogen DRI needs electricity below about US$40/MWh to beat carbon capture | [S09] |
| Mission Possible Partnership, Making Net-Zero Steel Possible (2022) | A near-zero primary steel premium of about US$175/t (about 40%) versus blast-furnace steel around 2030, adding about 2% to the price of a building | [S08] |
| IEA, Iron and Steel Technology Roadmap (2020) and Global Hydrogen Review (2025) | Hydrogen DRI needs power below about US$35/MWh to compete with gas DRI plus carbon capture; more than 200 low-emission hydrogen projects have reached investment decisions since 2020 | [S05][S79] |
| IEEFA (2022, 2026) | DR-grade ore is a bottleneck: about 3% of seaborne trade above 66% Fe in 2022; the high-grade market is expected to grow | [S75][S76] |
Source: as listed.
Read together, the studies support three conclusions for Central Africa. The opportunity is real: importers will pay for iron with a low carbon content, and they will pay more as carbon prices and border measures bite. The winners will be locations that combine DR-grade ore, low-cost firm clean electricity and port access, not merely one of the three. And the timeline is long: most studies place large-scale green iron trade in the 2030s and 2040s.
6.6 How much power would hydrogen need in Cameroon?
Figure 6.3 sets the electricity needed for hydrogen-based reduction against Cameroon’s power system. Supplying RC-1’s own iron units at full build-out, about 0.36 Mt of DRI a year, with hydrogen would take about 0.9 to 1.0 TWh of electricity a year for electrolysis alone. A full-size 1 Mt/yr module would take about 2.4 to 2.8 TWh. For comparison, Nachtigal, Cameroon’s largest hydro plant, injected 3.6 TWh in the twelve months to May 2026 [S52], and the whole country generated 8.12 TWh in 2025 [S50].
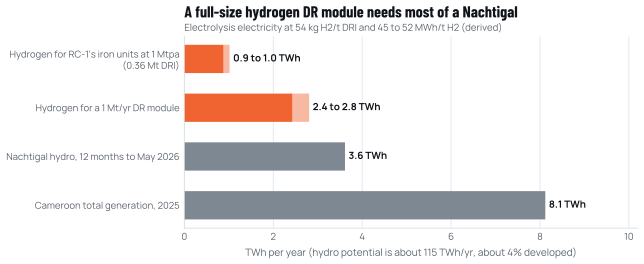
Source: hydrogen requirement [S17]; electrolyser efficiency [S05]; Nachtigal output [S52]; national generation [S50]; hydro potential [S53]. Derived by Cameroon Steel (Annex A).
The resource exists: Cameroon’s hydro potential is estimated at about 115 TWh a year, of which only about 4% is developed [S53]. The constraint is cost and firmness. At the purchase price of about 43.93 FCFA per kWh reported for the Memve’ele plant [S50][S103], about US$73 per MWh at a planning rate of 600 FCFA to the dollar (derived), new hydro is well above the US$35 to US$40 per MWh that the IEA and the ETC identify as competitive for hydrogen-based iron [S05][S09]. Older hydro sold under legacy contracts is cheaper, but its output is committed. Hydrogen-based iron in Cameroon would therefore need either very low-cost new hydro, a carbon price or premium that closes the gap, or both.
6.7 Gas: the bridge whose availability has just changed
A gas-based direct-reduction module, designed to accept hydrogen later, is the natural first step for ore-based iron in Central Africa, as it was in North Africa. Cameroon’s gas is produced mainly from the Sanaga Sud field near Kribi. In 2025, about 95% of national gas output was sold as feed to the floating liquefaction vessel Hilli Episeyo [S83]; the vessel’s charter ended and it left Cameroon in July 2026 [S84]. That frees gas in the near term, but the field is mature and its remaining reserves are not publicly certified, and the larger Yoyo-Yolanda resource has no final investment decision [S85]. A direct-reduction module would need a long-term supply contract backed by a reserve audit before it could be designed.
6.8 A stepwise, gated route
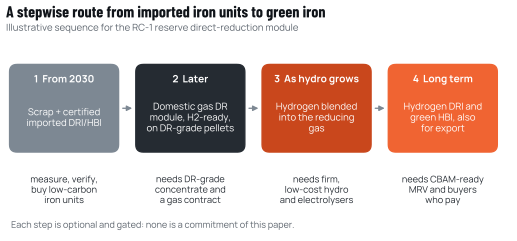
Figure 6.4 sets out how RC-1’s iron units could evolve. Each step is optional and conditional; none is a commitment of this paper.
Source: Cameroon Steel reference configuration RC-1 (planning estimate), reserve module [S90]; analysis in this chapter.
- From the first heat (targeted for the second half of 2030): imported scrap and certified DRI/HBI. Phase 1 melts scrap and buys DRI or HBI on the international market, with a verified carbon intensity and a contractual ceiling for each cargo. This is where the largest near-term savings are (Chapter 4).
- Later, after the main phases: a domestic gas-based module. If DR-grade concentrate and a gas contract are secured, a shaft furnace sized to RC-1’s needs (about 0.36 Mt of DRI a year at 1 Mtpa) or larger would replace imports. The RC-1 master plan reserves land for a direct-reduction module and pellet yard. On gas, its emissions would move from upstream into Cameroon Steel’s own Scope 1, at an intensity similar to the imported DRI it replaces; the gain is in value added and supply security, not yet in carbon.
- As hydro grows: hydrogen blending. Shaft furnaces can accept a rising share of hydrogen in the reducing gas. Each step would require electrolysers and firm power, and would lower the module’s emissions in proportion.
- Long term: hydrogen DRI and green HBI. At high hydrogen shares, the module could make iron at a few tenths of a tonne of CO2 per tonne, for RC-1’s own furnaces and for export as HBI into markets where CBAM and buyers reward low carbon. Under CBAM, DRI and HBI are covered goods, priced on their direct emissions from the outset (Chapter 5).
Table 6.3 Evidence needed before each step
| Step | Decision | Evidence required | Indicative timing |
|---|---|---|---|
| 1 | Carbon specification for purchased DRI/HBI | Supplier carbon data, verified to CBAM or ISO 14404 rules; market survey of low-carbon suppliers | Before Phase 1 procurement |
| 2 | Domestic gas-based DR module | Concentrate and pelletising study on Cameroonian ore; gas reserve audit and supply contract; module sizing; permits | Studies from 2027; decision after 2034 |
| 3 | Hydrogen blending | Firm low-carbon power at a competitive price; electrolyser supply; safety case | With new hydro capacity |
| 4 | Hydrogen DRI and HBI exports | Long-term offtake with a low-carbon premium; CBAM-ready monitoring; port bulk handling | Long term |
Source: Cameroon Steel analysis. Timings are indicative.
The KPIZ development plan already lists steelmaking linked to mineral exports among the zone’s clusters [S74], and Cameroon’s 2023 Mining Code provides for the local transformation of part of mine output [S86]. A stepwise green-iron route would align with both, while keeping each investment conditional on the evidence that justifies it.
Sources cited in this chapter
Bracketed markers refer to these sources; the full list is in the annex. Full list of sources
- S132025 World Direct Reduction Statistics. Midrex Technologies, Sep 2026.midrex.com/world-dri-statistics/world-dri-production-reaches-151-0-mt-…
- S15ENERGIRON technology: DRI-EAF production route using natural gas or H2. European Commission, Innovation Centre for Industrial Transformation, ref. 12 Feb 2026.innovation-centre-for-industrial-transformation.ec.europa.eu/innovativ…
- S17Hydrogen uses in ironmaking (Midrex presentation, H2@Scale). US Department of Energy, 1 Aug 2018.energy.gov/sites/prod/files/2018/08/f54/fcto-h2-scale-kickoff-2018-8-c…
- S01Sustainability Indicators 2025 report (2024 data; route table added February 2026). worldsteel, Nov 2025; upd. Feb 2026.worldsteel.org/wider-sustainability/sustainability-indicators/
- S18DRI-EAF implementation at Saarstahl and Dillinger steelworks (POWER4STEEL). European Commission, Innovation Centre for Industrial Transformation, ref. Jul 2025.innovation-centre-for-industrial-transformation.ec.europa.eu/innovativ…
- S06Achieving Net Zero Heavy Industry Sectors in G7 Members. International Energy Agency, 19 May 2022.iea.blob.core.windows.net/assets/c4d96342-f626-4aea-8dac-df1d1e567135/…
- S90Cameroon Steel reference configuration RC-1 (planning estimate): phases, planning values, balances and indicative schedule, edition 10 October 2026. Cameroon Steel, 10 Oct 2026.Cited by title and date
- S16Suez Steel sets new benchmark in energy consumption for DRI production. Danieli, 16 Apr 2026.danieli.com/en/news-media/news/suez-steel-sets-new-benchmark-energy-co…
- S83Données pétrolières 2025. Société Nationale des Hydrocarbures (SNH), Jun 2026.snh.cm/wp-content/uploads/2026/06/Donnees-petrolieres-2025.pdf
- S05Iron and Steel Technology Roadmap. International Energy Agency, Oct 2020.iea.blob.core.windows.net/assets/eb0c8ec1-3665-4959-97d0-187ceca189a8/…
- S09Mission Possible sectoral focus: Steel. Energy Transitions Commission, 2019 (Mission Possible, Nov 2018).energy-transitions.org/wp-content/uploads/2020/08/ETC-sectoral-focus-S…
- S75Iron Ore Quality a Potential Headwind to Green Steelmaking. Institute for Energy Economics and Financial Analysis (IEEFA), Jun 2022.ieefa.org/sites/default/files/2022-06/Iron%20Ore%20Quality%20a%20Poten…
- S1115 Insights on the Global Steel Transformation. Agora Industry, 15 Jun 2023.agora-industry.org/publications/15-insights-on-the-global-steel-transf…
- S76Global high-grade iron ore market is set to grow. Institute for Energy Economics and Financial Analysis (IEEFA), Mar 2026.ieefa.org/sites/default/files/2026-03/IEEFA_Global%20high-grade%20iron…
- S14Pedal to the Metal 2026. Global Energy Monitor, May 2026.globalenergymonitor.org/sites/default/files/2026-05/Pedal%20to%20the%2…
- S72Kribi: le Premier ministre, chef du gouvernement est là (foundation stone of the Kribi steel complex). Cameroon Tribune, 30 Dec 2024.cameroon-tribune.cm/article.html/68499/fr.html/details_2
- S03World Steel in Figures 2026. worldsteel, 4 Jun 2026.worldsteel.org/data/world-steel-in-figures/world-steel-in-figures-2026…
- S77Global Gateway: Namibia becomes pioneer for Africa’s green transition. European Commission, International Partnerships, 11 Apr 2025.international-partnerships.ec.europa.eu/news-and-events/news/global-ga…
- S78Namibia opens renewables-powered green iron plant. Energize, 15 Apr 2025.energize.co.za/article/namibia-opens-renewables-powered-green-iron-pla…
- S10Green Iron Corridors. RMI with the Green Hydrogen Catapult, 2024.rmi.org/insight/green-iron-corridors/
- S12Green Iron, Shared Gains. Agora Industry and Cambridge Econometrics, 8 Oct 2026.agora-industry.org/publications/green-iron-shared-gains
- S08Making Net-Zero Steel Possible. Mission Possible Partnership, Sep 2022.missionpossiblepartnership.org/action-sectors/steel
- S79Global Hydrogen Review 2025. International Energy Agency, 12 Sep 2025.iea.org/reports/global-hydrogen-review-2025
- S52Énergie: Nachtigal franchit le cap des 3,6 TWh injectés dans le réseau en un an. Journal du Cameroun, 15 Jun 2026.fr.journalducameroun.com/energie-nachtigal-franchit-le-cap-des-36-twh-…
- S50Rapport d’activités 2025 de l’ARSEL. ARSEL (electricity regulator, Cameroon), 7 Sep 2026.arsel-cm.org/wp-content/uploads/2026/09/Rapport-ARSEL-2025.pdf
- S53Cameroon: Energy (Country Commercial Guide). US International Trade Administration, 13 Apr 2026.trade.gov/country-commercial-guides/cameroon-energy
- S103Décision portant compensation tarifaire ENEO au titre de l’exercice 2024. ARSEL, 27 Dec 2024.arsel-cm.org/wp-content/uploads/2025/12/2024-Decsision-Tarifaire-2024-…
- S84Le navire usine quitte le Cameroun, le gaz s’arrête. Camer.be, 9 Jul 2026.camer.be/93911/12:1/le-navire-usine-quitte-le-cameroun-le-gaz-sarrete-…
- S85Cameroon’s SNH eyes Yoyo-Yolanda and new exploration blocks to sustain gas growth. Business in Cameroon, 6 Jul 2026.businessincameroon.com/energy/0607-16422-cameroon-s-snh-eyes-yoyo-yola…
- S74Zone industrialo-portuaire de Kribi (KPIZ): jusqu’à +8 points de croissance et 150 000 emplois attendus sur 15 ans. Investir au Cameroun, 4 Mar 2026.investiraucameroun.com/gestion-publique/0403-23163-zone-industrialo-po…
- S86Loi n° 2023/014 du 19 décembre 2023 portant Code minier. Republic of Cameroon (FAOLEX), 19 Dec 2023.faolex.fao.org/docs/pdf/cmr223180.pdf
Cite this chapter
Cameroon Steel (2026). Lower-carbon steel from Cameroon: it could reach a third of the world’s carbon intensity. White paper 06, chapter 6: Green iron: a long-term option for Central Africa, gated by ore, power and gas. CS-WP-06. https://www.cameroon-steel.com/en/library/lower-carbon-steel/green-iron/
Source