White paper 09 · Chapter 6
Fiscal effects: substitution moves revenue from the border to the domestic economy
Import substitution changes where taxes are collected more than how much is collected. When domestic steel replaces imported billets, the State loses the 10% customs duty on the displaced imports, about 3.0 to 3.3 bn FCFA a year for every 100,000 tonnes [P24], derived. If the domestic steel is melted from imported scrap and hot briquetted iron, the 10% duty on those inputs replaces almost all of that loss; if it is made from domestic iron units, the border revenue disappears and must be recovered from taxes on domestic activity: corporate income tax, payroll taxes and contributions, value-added tax on domestic value added, and royalties and gas taxes upstream. The investment-incentive ordinance of July 2025 is generous during construction and conditional in operation, offering a profit-tax credit of up to 75% of the investment for large projects, capped each year at half of declared profit [W08]. This chapter maps these effects. It is illustrative by design: it does not estimate a fiscal balance for any specific project, because that would require investment and profit figures that this paper does not publish.
In this chapter (5)
- 6.1 Eight instruments touch a steelworks and its supply chain
- 6.2 At the border, substitution is close to fiscally neutral while iron units are imported
- 6.3 Domestic revenue: profits, wages and the upstream chain
- 6.4 The 2025 incentive ordinance is generous in construction and conditional in operation
- 6.5 Principles for a fiscally responsible steel policy
6.1 Eight instruments touch a steelworks and its supply chain
Table 6.1 lists the taxes and levies that apply to steel imports, to a domestic steelworks and to its upstream suppliers. Four features matter for the analysis that follows.
Customs duties are levied on imports at the border. Under the common external tariff (CET) applied in 2023, billets, scrap, direct reduced iron and iron ore each bear 10%, sections 10%, rebar 20% and the most common wire-rod line 5% [P24]. A 0.2% African Union integration levy applies to imports from outside the African Union [P19]. The new harmonised ECCAS-CEMAC tariff applied in Cameroon from 1 January 2026 uses bands of 0 to 40%, but its steel lines had not been published at the time of writing [P23].
Value-added tax is neutral between imports and domestic production. VAT at 19.25% is charged on imports at the border and on domestic sales, with credit for tax paid on inputs; exports are zero-rated [P19]. Replacing an import with a domestic product therefore moves the point of collection rather than the amount of VAT, except that domestic production generates VAT on its own value added at each stage. For an exporting works, prompt refund of VAT credits on inputs becomes a condition of competitiveness.
Corporate income tax applies to profits, after incentives. The standard rate is 33%, including the 10% additional council tax, for companies with turnover above 3 bn FCFA, and a minimum tax of 2.2% or 5.5% of turnover applies depending on the tax regime [W05].
Payroll contributions and personal income tax apply to wages from the first day of operation. Employers pay 11.2% of salary to the national social insurance fund (CNPS), capped at a monthly salary of 750,000 FCFA, plus 1.5% to the housing fund (Crédit Foncier) and 1% to the National Employment Fund; employees pay 4.2% to the CNPS and 1% to the housing fund [P19][W06]. Personal income tax is progressive, reaching an effective top rate of 38.5% on net income above 5 million FCFA a year [W07].
Table 6.1 Taxes and levies relevant to steel imports, a domestic steelworks and its supply chain, Cameroon, 2026
| Instrument | Rate or basis | Applies to | Source |
|---|---|---|---|
| Common external tariff | 10% billets, scrap, DRI, ore; 10% sections; 20% rebar; 5% wire rod (7213.91) | Imports (2023 schedule; 2026 steel lines unpublished) | [P24][P23] |
| African Union integration levy | 0.2% | Imports from outside the AU | [P19] |
| Value-added tax | 19.25%; exports zero-rated | Imports and domestic sales | [P19] |
| Corporate income tax | 33% (turnover above 3 bn FCFA); minimum tax 2.2% or 5.5% of turnover | Company profits | [W05] |
| Employer social and payroll contributions | CNPS 11.2% (capped at 750,000 FCFA/month); housing fund 1.5%; employment fund 1% | Gross salaries | [P19][W06] |
| Employee contributions and income tax | CNPS 4.2%; housing fund 1%; income tax up to 38.5% | Gross salaries | [W06][W07] |
| Environmental tax (Finance Law 2026) | 5,000 FCFA per tonne of reinforcing bar (fer à béton) | Local producers and importers alike | [P19][P11] |
| Special tax on petroleum products, natural gas | 70 FCFA per m³ from 2023; applicability to industrial gas not confirmed | Gas supply (upstream) | [E11] |
Source: as cited in the table.
6.2 At the border, substitution is close to fiscally neutral while iron units are imported
The customs revenue that a domestic long-products industry could displace is modest. On the 2023 import composition, the CET yielded about US$15.2 million on billets, US$2.6 million on sections, US$0.4 million on wire rod and US$0.7 million on rebar imported under derogation, plus US$5.8 to 11.6 million on fabricated structures, which bear 10% or 20% depending on the line [C06][P24], derived. In total that is about US$25 to 30 million, or 15 to 18 bn FCFA at the 2023 average exchange rate [W13], derived.
Figure 6.1 shows what happens at the margin. Consider 100,000 tonnes a year of domestic rebar that displaces rebar rolled by existing mills from imported billets. The billets no longer imported would have paid about 3.0 to 3.3 bn FCFA in customs duty [P24][G34], derived. If the new rebar is melted from imported scrap and HBI (scenario S1 in Chapter 9), those inputs pay 10% duty too, about 2.8 to 3.1 bn FCFA, and the border loss almost disappears [P24][G34][W10], derived. Payroll-linked taxes and contributions on the roughly 170 direct jobs per 100,000 tonnes implied by RC-1 add a further 0.2 to 0.4 bn FCFA a year [F][P19][W06], derived. The net effect at the border and on payroll lies between minus 0.4 and plus 0.5 bn FCFA per 100,000 tonnes: close to neutral.
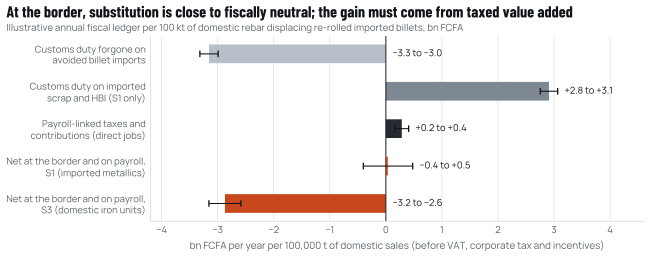
Source: CET [P24]; prices AISU [G34] and SteelOrbis [W10]; payroll rates PwC [P19][W06][W07]; jobs per tonne RC-1 [F]; wages assumed at 300,000 to 600,000 FCFA per month and effective income tax at 8 to 15% (Annex A). Illustrative; corporate income tax, VAT and incentives excluded.
With domestic iron units (scenario S3), the State collects no duty on the inputs, so the border account shows a loss of about 2.6 to 3.2 bn FCFA per 100,000 tonnes after payroll taxes. That loss must be recovered from taxes on domestic value added, which is exactly what domestic iron units create: profits taxed at 33% once incentives expire, wages, and upstream activity in mining, gas and transport. The fiscal case for import substitution is therefore the same as its foreign-exchange case. It rests on value added retained in the country, not on the border.
6.3 Domestic revenue: profits, wages and the upstream chain
Corporate income tax. At the statutory rate, each 1 bn FCFA of taxable profit yields 330 million FCFA of tax [W05]. How much a steelworks pays depends on its margins, which depend on its competitiveness at border prices (Chapter 7), and on the incentive regime. An industry that survives only behind a prohibition pays tax on rents extracted from domestic buyers; an industry that is competitive at import parity pays tax on genuine value added. The second is the sustainable base.
Payroll taxes. For Phase 1, an illustrative wage bill of 1.8 to 3.6 bn FCFA a year for about 500 employees would generate about 0.5 to 1.2 bn FCFA a year in employer and employee contributions and personal income tax, rising to about 1.1 to 2.7 bn FCFA at full capacity with about 1,100 employees [F][P19][W06][W07], derived and illustrative. These flows begin with operations and are not affected by profit-tax incentives.
Environmental tax. The 2026 Finance Law introduced an environmental tax of 5,000 FCFA per tonne of reinforcing bar (fer à béton), payable by local producers and importers alike [P19][P11]. For 300,000 tonnes of rebar and wire rod sold domestically, the gross amount would be up to 1.5 bn FCFA a year if all products were within its scope. Because existing producers already pay it, new production that displaces them changes the total little.
Upstream taxes. With domestic iron units, part of the fiscal base moves upstream. Natural gas is subject to a special tax of 70 FCFA per cubic metre introduced in 2023 [E11]; if it applied to gas used for direct reduction, it would amount to roughly 18,000 FCFA per tonne of direct reduced iron at 10 GJ of gas per tonne [E11][F], derived, a material cost whose applicability to industrial users should be clarified before any direct-reduction investment. Iron-ore mining pays ad valorem royalties under the 2023 Mining Code, and the State holds at least 10% of free, non-dilutable equity in mining companies [O36]; the royalty rate for iron ore was not found in accessible summaries [O36].
6.4 The 2025 incentive ordinance is generous in construction and conditional in operation
Ordinance No. 2025/002 of 18 July 2025 on investment incentives, ratified by Law No. 2025/015 of 17 December 2025, repeals the 2013 investment-incentive law and brings economic zones and public-private partnerships into a single framework [W08][R15]. Its structure matters for any industrial investor and for the fiscal cost of industrial policy (Table 6.2).
Eligibility. Heavy industry is an eligible sector (Article 3), while the mining, upstream petroleum and gas sectors, governed by their own codes, are excluded [W08]. Every applicant must submit a programme for local skills, technology transfer and priority recruitment of Cameroonian workers and subcontractors, and evidence that the financing is available (Article 6) [W08]. New projects must meet at least two of five criteria (Article 7): at least one direct job for each 50 million FCFA of planned investment; for industrial projects, national natural resources accounting for at least 50% of the value of inputs, excluding labour, water, energy and telecommunications, unless they are unavailable; an increase in value added of at least 30%; or exports and shipments within the customs union of at least 25% of turnover; the fifth, 40% Cameroonian products, applies to distribution [W08].
Installation phase (up to five years). Equipment and materials directly linked to the investment programme are exempt from customs duties and import VAT; registration duties on leases, land transfers, supply contracts and capital increases are waived; VAT on foreign services linked to the project and on loan interest is exempt; and property tax and the business licence are waived (Article 10) [W08].
Operating phase (up to five years; seven in economic zones). For investments above 5 bn FCFA (category C), the ordinance offers a reduced customs duty of 5% on equipment and spare parts, exemption from export duties, a credit against profit tax equal to 75% of the investment made, capped each year at half of declared profit and carried forward for up to five years (80% in priority development zones), five-year loss carry-forward and accelerated depreciation at twice the normal rate (Article 11) [W08]. Projects in economic zones benefit from an operating phase extended to seven years, inward-processing relief and temporary-admission arrangements (Articles 14 and 15) [W08]. The ports of Douala and Kribi are classified as economic zones [P10].
Transfers. Subject to the CEMAC foreign-exchange regulation, investors may transfer dividends, interest and liquidation proceeds freely (Article 19) [W08]. This is the channel through which part of the foreign exchange saved by a domestic works can flow back out, a point Chapter 9 takes into account.
Table 6.2 The investment-incentive framework of Ordinance No. 2025/002 as it applies to a large industrial project
| Element | Provision | Article |
|---|---|---|
| Eligible sector | Heavy, automotive and manufacturing industry; mining, upstream oil and gas excluded | 3 |
| Common conditions | Local skills, technology-transfer and local-hiring programme; proof of available financing | 6 |
| Specific criteria (new projects: two of five) | One direct job per 50 m FCFA invested; at least 50% national natural-resource inputs (industry); value added up at least 30%; exports or intra-CEMAC shipments at least 25% of turnover; (distribution: 40% Cameroonian products) | 7 |
| Installation phase (up to 5 years) | Customs duty and import VAT exemption on equipment; registration-duty waivers; VAT exemption on foreign services and loan interest; property tax and business licence waived | 10 |
| Operating phase, category C (above 5 bn FCFA), up to 5 years | 5% customs duty on equipment and spares; export-duty exemption; profit-tax credit of 75% of investment, capped at half of declared profit per year, carried forward up to 5 years (80% in priority zones); 5-year loss carry-forward; double-rate depreciation | 11 |
| Priority development zones | Inward processing; 50% abatement of duties on raw materials not available locally; further exemptions | 12 |
| Economic zones | Articles 10 and 11 apply; operating phase extended to 7 years; inward processing; temporary admission | 14, 15 |
| Transfers | Free transfer of dividends and capital, subject to CEMAC exchange regulation | 19 |
Source: Ordonnance n° 2025/002 du 18 juillet 2025 fixant les incitations à l’investissement en République du Cameroun [W08]; ratification by Law No. 2025/015 [R15]; economic-zone status of Kribi port [P10].
Two observations follow. First, the ordinance’s own criteria favour the features that this paper identifies as economically valuable: national natural-resource inputs, value added and exports. An electric arc furnace that melts imported scrap and HBI would not meet the 50% national-resource criterion in its early phases, but the criterion becomes attainable as domestic scrap collection and Cameroonian iron units come on stream. Second, the profit-tax credit is large relative to profits in the early years of operation; depending on how the annual cap is applied in practice, profit tax could be substantially reduced for five to seven years. That is a legitimate tool to attract capital-intensive investment, but it means that the fiscal return in the first decade comes mainly from payroll, upstream activity and the multiplier effects of Chapter 4, not from corporate tax.
6.5 Principles for a fiscally responsible steel policy
With high debt-distress risk and IMF pressure to raise non-oil revenue and contain tax expenditures (Chapter 1) [P09][P32], the fiscal design of steel policy should follow four principles.
- Prefer instruments that do not cost the budget. A tariff raises revenue; a prohibition does not; a procurement preference costs only the margin of preference. Tax holidays should be granted against measurable criteria, not by sector alone.
- Tie incentives to the Article 7 criteria and monitor them. Jobs, national inputs, value added and exports are measurable. Publishing the tax expenditure of each convention, and reviewing compliance annually, would protect the credibility of the regime.
- Recover border revenue from domestic value added. As iron units become domestic and customs revenue falls, the corresponding gain in profits, wages and upstream activity should be visible in the tax base. Clarifying the application of the gas tax and of iron-ore royalties in advance would let investors price them and let the State count on them.
- Keep exporters whole on VAT and duties. Inward processing and prompt VAT refunds are what make export competitiveness possible; they are not concessions but conditions of the zero-rating principle.
Sources cited in this chapter
Bracketed markers refer to these sources; the full list is in the annex. Full list of sources
- P24WITS TRAINS API: Cameroon reported MFN tariffs by HS6 (2023). World Bank / UNCTAD.wits.worldbank.org/API/V1/SDMX/V21/datasource/TRN/reporter/120/partner…
- P19Cameroon, Republic of: Corporate, Other taxes. PwC Worldwide Tax Summaries, reviewed 14 Aug 2026.taxsummaries.pwc.com/republic-of-cameroon/corporate/other-taxes
- P23Cameroon applies CEEAC common external tariff from January 1, 2026. Business in Cameroon, 12 Jan 2026.businessincameroon.com/public-management/1201-15594-cameroon-applies-c…
- W05Cameroon, Republic of: Corporate, taxes on corporate income. PwC Worldwide Tax Summaries, reviewed 14 Aug 2026.taxsummaries.pwc.com/republic-of-cameroon/corporate/taxes-on-corporate…
- W06Cameroon, Republic of: Individual, other taxes (social security, housing fund, employment fund). PwC Worldwide Tax Summaries.taxsummaries.pwc.com/republic-of-cameroon/individual/other-taxes
- W07Cameroon, Republic of: Individual, taxes on personal income. PwC Worldwide Tax Summaries, reviewed 14 Aug 2026.taxsummaries.pwc.com/republic-of-cameroon/individual/taxes-on-personal…
- P11Cameroun: les principales innovations de la loi de finances pour 2026. Deloitte Société d’Avocats, 24 Mar 2026.blog.avocats.deloitte.fr/cameroun-les-principales-innovations-de-la-lo…
- E11Industrial gas: Cameroon suspends GDC’s 20% price hiking plan. Business in Cameroon, 18 Jul 2023.businessincameroon.com/energy/1807-13291-industrial-gas-cameroon-suspe…
- C06UN Comtrade public API: Cameroon (reporter 120), HS 72/73 and 6-digit lines, 2019-2023. UN Statistics Division.comtradeapi.un.org/public/v1/preview/C/A/HS?reporterCode=120&period=20…
- W13Euro foreign exchange reference rates, US dollar, monthly averages (series EXR.M.USD.EUR.SP00.A). European Central Bank.data-api.ecb.europa.eu/service/data/EXR/M.USD.EUR.SP00.A
- G34Weekly steel prices (archive 40468). Arab Iron & Steel Union (AISU), 3 Oct 2026.aisusteel.org/en/archives/40468
- W10Global HBI market bullish amid tight supply, ex-Libya tender closure to give further direction. SteelOrbis, 15 May 2026.steelorbis.com/steel-prices/steel-prices-market-analyses/scrap-and-raw…
- FCameroon Steel reference configuration RC-1 (planning estimate), edition 10 October 2026 (RC-1.1). Cameroon Steel, 10 Oct 2026.Cited by title and date
- O36Mining 2026: Cameroon (Chazai Wamba). Chambers Global Practice Guides, updated 27 Jan 2026.practiceguides.chambers.com/practice-guides/mining-2026/cameroon
- W08Ordonnance n° 2025/002 du 18 juillet 2025 fixant les incitations à l’investissement en République du Cameroun (certified copy). Presidency of the Republic, copy hosted by LEGECAM, 18 Jul 2025.legecam.cm/wp-content/uploads/2025/08/ordonnance_n_2025_002_du_18_07_2…
- R15Ordonnance n° 2025/002 du 18 juillet 2025 fixant les incitations à l’investissement; Loi n° 2025/015 du 17 décembre 2025 portant ratification. Presidency of the Republic of Cameroon, 18 Jul 2025; 17 Dec 2025.prc.cm/fr/actualites/actes/ordonnances/7897-ordonnance-n-2025-002-du-1…
- P102024 Investment Climate Statements: Cameroon. US Department of State, 2024.state.gov/reports/2024-investment-climate-statements/cameroon/
- P09IMF Executive Board concludes 2026 Article IV consultation with Cameroon (PR 26/096). IMF, 30 Mar 2026.imf.org/en/news/articles/2026/03/30/pr-26096-cameroon-imf-executive-bo…
- P32IMF staff concludes Post-Financing Assessment mission to Cameroon (PR 26/314). IMF, 1 Oct 2026.imf.org/en/news/articles/2026/10/01/pr26314-imf-staff-concludes-assesm…
Cite this chapter
Cameroon Steel (2026). Domestic steel saves foreign exchange only when it competes at border prices. White paper 09, chapter 6: Fiscal effects: substitution moves revenue from the border to the domestic economy. CS-WP-09. https://www.cameroon-steel.com/en/library/economics-of-domestic-steel/fiscal-effects/
Source