White paper 09 · Chapter 5
Employment: about 500 direct jobs in Phase 1 and 1,100 at full capacity, with a wide range beyond
Cameroon Steel’s reference configuration plans about 500 direct jobs for the first phase of 0.3 Mtpa (range 450 to 550), about 800 workers at the peak of Phase 1 construction, and an indicative 1,100 direct jobs at the full 1 Mtpa (range 900 to 1,300) [F]. Indirect and induced employment is harder to pin down. Published multipliers for steel range from about 3 to about 10 total jobs per direct job, but the higher values describe economies with deep domestic supply chains and are upper bounds for Cameroon [P01][P02][W01]. Applied with that caution, the works would support roughly 2,700 to 8,000 jobs in total at full capacity. The number matters less than three other features: whether the jobs are additional rather than displaced from existing mills, whether they are formal and skilled, and whether the supply chain behind them is domestic. This chapter sets out the evidence without inventing a multiplier for Cameroon.
In this chapter (8)
- 5.1 Direct employment is planned at about 500 in Phase 1 and 1,100 at full capacity
- 5.2 Direct jobs per million tonnes vary tenfold, with route and scope
- 5.3 Indirect and induced jobs: published multipliers range from 3 to 10 total jobs per direct job
- 5.4 Why Cameroon’s multiplier will be at the low end at first
- 5.5 Illustrative employment at each phase, with the range made explicit
- 5.6 Net, not gross: the jobs that already exist must be counted
- 5.7 Where the jobs would be: Kribi, its zone and the construction phase
- 5.8 Job quality: skills, safety and local supply
5.1 Direct employment is planned at about 500 in Phase 1 and 1,100 at full capacity
The RC-1 planning basis sets Phase 1 staffing, for a single electric arc furnace of the 40 t class with ladle furnace, billet caster, rebar mill and wire-rod mill, at about 500 direct employees: some 300 operators, 100 technicians, 50 engineers and 50 administrative staff [F]. The range is 450 to 550, depending on the degree of automation and outsourcing of services such as security, catering and transport [F]. Construction of Phase 1 is expected to employ about 800 workers at its peak, in a range of 600 to 1,000 [F]. At full capacity of 1 Mtpa, after two further phases for sections and heavy sections, the indicative staffing is 1,100 direct employees, in a range of 900 to 1,300; the planning basis assumes that labour productivity improves with scale, because a second and third melt line and larger mills do not require proportionally more staff [F]. The target is for Cameroonian nationals to fill about 90% of operating positions by the fifth year (range 85 to 95%) [F].
These figures are consistent with the public record. Press coverage of the foundation-stone ceremony at Mboro on 30 December 2024 reported "more than 2,000 direct and indirect jobs" [X02], a figure compatible with Phase 1 direct employment plus the indirect employment set out below.
5.2 Direct jobs per million tonnes vary tenfold, with route and scope
Direct employment per million tonnes of capacity varies widely across the industry, and comparisons must be made carefully (Figure 5.1). Modern US rebar micro-mills, which melt scrap and roll a narrow product range with high automation, employ about 500 people per million tonnes: Nucor’s Lexington mill was announced with about 200 permanent jobs for 430,000 tons a year, and Commercial Metals Company’s Berkeley County mill with 230 jobs for 500,000 tons (read as US short tons, the unit of that company’s reports; about 0.39 and 0.45 Mt) [T20][T23], derived. The European steel industry as a whole employs about 2,040 people per million tonnes of output (298,000 direct jobs in 2024 for an average annual output of 146 Mt) [P02], derived. In Africa, Prometal 4 and 5 in Douala were inaugurated with 1,000 direct jobs for about 360,000 tonnes, about 2,800 per million tonnes [C25]; and Devki’s ore-based plant at Kwale in Kenya was announced with 2,500 direct jobs for 500,000 tonnes, about 5,000 per million tonnes, because it includes ironmaking [A23], derived.
RC-1’s planned Phase 1 staffing equals about 1,670 direct jobs per million tonnes and the full-capacity indication about 1,100 [F], derived. Both sit within the range of the published cases, between the highly automated US micro-mills and the more labour-intensive African plants. If a direct-reduction module were added later, employment per tonne would rise, as the Devki example shows.
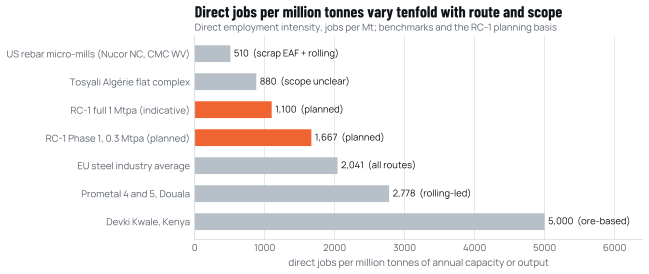
Source: Nucor [T20]; West Virginia Public Broadcasting [T23]; Algérie Eco [A25] (scope of the Tosyali workforce figure unclear); EUROFER [P02]; Journal du Cameroun [C25]; Capital FM Kenya [A23]; Cameroon Steel RC-1 [F]. Ratios derived by Cameroon Steel.
5.3 Indirect and induced jobs: published multipliers range from 3 to 10 total jobs per direct job
Steel’s employment case traditionally rests on its supply chain. Four sets of published estimates are relevant (Figure 5.2).
World. worldsteel and Oxford Economics estimated that the steel industry employed 6.1 million people directly in 2017 and that "for every 2 jobs in the steel sector, 13 more jobs are supported" in its supply chain, 40.5 million in all, with a further 49.3 million jobs facilitated in steel-using sectors [P01]. Expressed as total jobs per direct job in the industry and its supply chain, the ratio is 7.5.
European Union. EUROFER estimates 298,000 direct jobs, 1.55 million indirect jobs and 0.70 million induced jobs in 2024, a Type I multiplier (direct plus indirect, per direct job) of 6.2 and a Type II multiplier (including induced) of 8.6 [P02].
United States. The Economic Policy Institute estimates that every 100 jobs in iron and steel mills and ferroalloy manufacturing support 618.2 jobs at suppliers and 305.6 induced jobs, 923.7 indirect jobs in all, the equivalent of a Type II multiplier of about 10.2 [W01]. For construction, the same study gives 226.1 indirect jobs per 100 direct jobs [W01].
South Africa. The Steel and Engineering Industries Federation of Southern Africa (SEIFSA) cites an employment multiplier of six for the steel sector [W03]. The definition behind that figure is not published in the source.
Cameroon Steel’s planning basis. RC-1 estimates about 1,000 indirect jobs for the 500 direct jobs of Phase 1, a ratio of three total jobs per direct job [F].
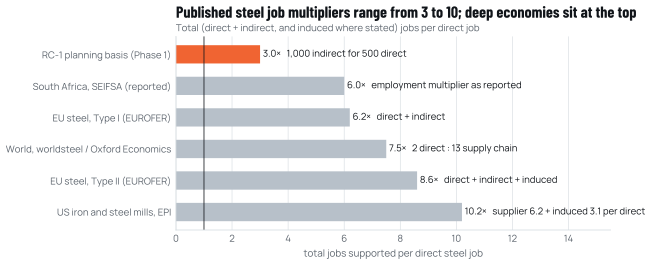
Source: Cameroon Steel RC-1 [F]; Engineering News, 26 January 2024 (SEIFSA) [W03]; EUROFER, European Steel in Figures 2025 [P02]; worldsteel / Oxford Economics (2019) [P01]; Economic Policy Institute (2019), Appendix Table A1 [W01].
5.4 Why Cameroon’s multiplier will be at the low end at first
Three reasons argue for treating the European, global and US figures as upper bounds rather than estimates for Cameroon.
First, the supply chain is thinner. In Europe and the United States, a steelworks buys refractories, electrodes, alloys, industrial gases, spare parts, engineering services and equipment from domestic suppliers who employ many people. In Cameroon, most of these items are imported. The Cameroonian social accounting matrix for 2016 shows the consequence: the employment generated per million FCFA of final demand for basic metal products, 0.54 jobs, was less than half that for construction, 1.13 jobs [W02]. The difference reflects the import content of the metal sector rather than any lack of labour intensity.
Second, the iron units are imported in the early phases. Much of the supply-chain employment in the global estimates sits in mining, ironmaking, coal and transport of raw materials [P01]. A works that melts imported scrap and HBI creates those jobs abroad. Domestic scrap collection and, later, Cameroonian ore and gas would bring part of them home.
Third, induced employment depends on where wages are spent. Type II multipliers count the jobs created when employees spend their wages. In an economy where a large share of consumer goods is imported, a smaller share of that spending creates domestic jobs. The induced component should therefore be treated with particular caution.
The Cameroonian context also explains why even modest numbers of formal jobs matter. The JRC study cites the government’s objective of reducing underemployment from 75.8% to 50.1% by 2030 [W02]. Formal industrial jobs with social security coverage, skills and career paths are scarce relative to that need.
5.5 Illustrative employment at each phase, with the range made explicit
Table 5.1 combines the RC-1 direct employment figures with the lower and upper ends of the multiplier evidence. The lower end uses the planning basis (three total jobs per direct job); the upper end uses the EU Type I multiplier of 6.2, which already exceeds what a thin supply chain is likely to support. Induced jobs are excluded. The result is a range, not a forecast.
Table 5.1 Illustrative direct and total employment supported, RC-1 phases (planned and indicative)
| Phase | Finished output | Direct jobs (RC-1) | Status | Total jobs at 3.0 times direct (planning basis) | Total jobs at 6.2 times direct (EU Type I, upper bound) |
|---|---|---|---|---|---|
| Phase 1 construction (peak) | n/a | 600 to 1,000 workers | planned | n/a (temporary) | n/a (temporary) |
| Phase 1 operation | 0.3 Mtpa | 450 to 550 (central 500) | planned | 1,350 to 1,650 | 2,790 to 3,410 |
| Full operation | 1.0 Mtpa | 900 to 1,300 (central 1,100) | indicative | 2,700 to 3,900 | 5,580 to 8,060 |
| Memo: share of nationals in operations by year 5 | 85 to 95% (target 90%) | target |
Source: Cameroon Steel RC-1 [F]; multipliers from RC-1 [F] and EUROFER [P02]. Illustrative; derived by Cameroon Steel. Intermediate phases are not shown because RC-1 does not set staffing for them.
5.6 Net, not gross: the jobs that already exist must be counted
Employment estimates for a new plant usually count gross jobs. Policy should count net jobs, after allowing for jobs lost elsewhere. This matters in Cameroon because the domestic steel industry already exists. The Ocitram association, whose members include the main steel and aluminium producers, reported about 5,000 jobs in May 2026 [C30], and Prometal alone opened two plants with 1,000 direct jobs in 2024 [C25]. Rebar rolling capacity is about three and a half times domestic rebar demand, and the sector runs at about half capacity [C30][C38].
If a new works simply added rebar capacity and sold into the domestic market by displacing existing producers, a large part of its gross employment would be offset by losses at those producers. The net effect would be smaller still if the new capacity relied on the same import prohibition and price arrangements (Chapter 3). Conversely, two features of a phased works would make its jobs largely additional:
- Products not made locally. Medium and heavy sections, now imported, would create jobs without displacing domestic production (Chapter 2).
- Iron units for existing mills. A domestic supply of billets would relieve the binding constraint on existing re-rollers, which now borrow to import billets and run at about half capacity [C38][C40]. Higher utilisation at those mills would create jobs there too: a positive backward linkage from the new works to the existing industry rather than a displacement.
The employment case for domestic steel is therefore strongest when the works fills gaps in the chain rather than duplicating its most crowded segment.
5.7 Where the jobs would be: Kribi, its zone and the construction phase
Employment effects are also local. The works would be located in the Kribi industrial-port zone, whose new development company was launched in February 2026 with expectations, reported at the launch, of up to 150,000 jobs across the zone over fifteen years and with steelmaking linked to mineral exports listed among its clusters [W31]. Labour-market statistics for Kribi itself (unemployment, skills and wages) are not published, which is itself an evidence gap (Chapter 11). What is clear is that a single works of 500 to 1,100 permanent employees would be among the larger industrial employers of the zone, and that its suppliers (transport, maintenance, catering, security, scrap collection) would be drawn partly from the town and partly from Douala and Yaoundé.
The construction phase has a different profile. RC-1 plans a peak of about 800 workers for Phase 1 construction, in a range of 600 to 1,000 [F], most of them for civil works, steel erection, mechanical installation and electrical works over about two years, followed by smaller peaks for later phases. These jobs are temporary but valuable: they are the main channel through which local contractors acquire industrial references, and the 2025 incentive ordinance requires investors to give priority to local subcontractors and contractors (Article 6) [W08]. A deliberate local-content plan for construction, with packages sized for Cameroonian firms, training for welders and riggers, and transparent recruitment through local authorities, would turn a temporary peak into lasting capability.
Two risks need management. In-migration to a growing port town raises demand for housing and services faster than municipal capacity, and recruitment expectations can exceed the number of jobs available. Both argue for publishing staffing plans early, recruiting transparently and coordinating with the zone developer and the municipality.
5.8 Job quality: skills, safety and local supply
Steel jobs are formal, technical and comparatively well paid, and their value lies as much in the skills they build as in their number. Cameroon has an engineering base but no dedicated ferrous-metallurgy programme. The École Nationale Supérieure Polytechnique in Yaoundé trains industrial, mechanical, electrical and civil engineers but has no metallurgy or materials department [K02]; the Institut Universitaire de Technologie in Douala teaches mechanical production, industrial maintenance and thermal engineering to more than 3,000 students [K08]; the schools of mines and mineral engineering at the University of Ngaoundéré cover the ore side [K03][K04]; and the University of Ebolowa, the closest to Kribi, was created in 2022 [K09]. A works of this kind needs furnace operators, casters, rolling-mill crews, electricians, instrument technicians, maintenance mechanics and laboratory staff in numbers that the education system does not now produce, and the 2025 ordinance requires each investor to submit a programme for local skills (Article 6) [W08].
Safety is part of job quality. A new works built and operated to international occupational health and safety standards, with certified quality systems, raises the standard of the sector as well as its size.
Sources cited in this chapter
Bracketed markers refer to these sources; the full list is in the annex. Full list of sources
- FCameroon Steel reference configuration RC-1 (planning estimate), edition 10 October 2026 (RC-1.1). Cameroon Steel, 10 Oct 2026.Cited by title and date
- X02Cameroun, Complexe moderne de sidérurgie de Kribi: le PM Joseph Dion Ngute effectue la pose de la première pierre. Camer.be, 5 Jan 2025.camer.be/87795/12:1/cameroun-complexe-moderne-de-siderurgie-de-kribi-l…
- T20Nucor to build new rebar micro mill in North Carolina. Nucor Corp., 7 Apr 2022.nucor.com/news-release/nucor-to-build-new-rebar-micro-mill-in-north-ca…
- T23Rebar manufacturing facility coming to Eastern Panhandle. West Virginia Public Broadcasting, 8 Dec 2022.wvpublic.org/story/economy/rebar-manufacturing-facility-coming-to-east…
- P02European Steel in Figures 2025. EUROFER, Jun 2025.eurofer.eu/assets/publications/brochures-booklets-and-factsheets/europ…
- C25Prometal inaugure deux usines évaluées à 57 milliards F. Journal du Cameroun, 19 Jan 2024.fr.journalducameroun.com/prometal-inaugure-deux-usines-evaluees-a-57-m…
- A23Devki opens Sh50bn steel plant in Kwale. Capital FM Kenya, 20 Nov 2022.capitalfm.africa/devki-opens-sh50bn-steel-plant-in-kwale/
- A25Tosyali Algérie: mise en service du complexe des tôles d’acier plat (2,5 Mt). Algérie Eco, 28 Nov 2024.algerie-eco.com/2024/11/28/tosyali-algerie-mise-en-service-du-complexe…
- P01Economic and social impact of the global steel industry (infographic). worldsteel / Oxford Economics, May 2019.worldsteel.org/wp-content/uploads/Steel-social-and-economic-impact.pdf
- W01Updated employment multipliers for the U.S. economy (J. Bivens). Economic Policy Institute, 23 Jan 2019.epi.org/publication/updated-employment-multipliers-for-the-u-s-economy…
- W03More than 290 000 jobs on the line as steel sector continues its decline, Seifsa warns (S. Burger). Engineering News (Creamer Media), 26 Jan 2024.engineeringnews.co.za/article/more-than-290-000-jobs-on-the-line-as-st…
- W02Environmental sustainability and job creation: a SAM-based approach for Cameroon (A. El Meligi, V. Ferreira, V. Nechifor, E. Ferrari). European Commission Joint Research Centre; GTAP resource 11157 via AgEcon Search, 2023.ageconsearch.umn.edu/record/333428
- C30Production: les acteurs en présence. Cameroon Tribune, 11 May 2026.cameroon-tribune.cm/article.html/76600/fr.html/details_2
- C38Cameroun: le groupe Prometal décroche 26 milliards FCFA auprès d’Afreximbank…. Sikafinance, 30 Sep 2026.sikafinance.com/marches/cameroun-le-groupe-prometal-decroche-26-millia…
- C40Cameroun: Prometal décroche 26,2 milliards FCFA d’Afreximbank. Camer.be, 1 Oct 2026.camer.be/actualites/economie/cameroun-prometal-decroche-262-milliards-…
- W31Zone industrialo-portuaire de Kribi (KPIZ): jusqu’à +8 points de croissance et 150 000 emplois attendus sur 15 ans. Investir au Cameroun, 4 Mar 2026.investiraucameroun.com/gestion-publique/0403-23163-zone-industrialo-po…
- W08Ordonnance n° 2025/002 du 18 juillet 2025 fixant les incitations à l’investissement en République du Cameroun (certified copy). Presidency of the Republic, copy hosted by LEGECAM, 18 Jul 2025.legecam.cm/wp-content/uploads/2025/08/ordonnance_n_2025_002_du_18_07_2…
- K02ENSPY homepage (departments). ENSP Yaoundé, n.d..polytechnique.cm/
- K08ISTD / IUT Douala (homepage). iut-dla.cm, n.d..iut-dla.cm/
- K03EGEM, fiche d’identification. Université de Ngaoundéré, n.d..univ-ndere.cm/fr/etablissements/egem/
- K04EGCIM, fiche. Université de Ngaoundéré, n.d..univ-ndere.cm/fr/etablissements/egcim/
- K09Université d’Ebolowa (tertiary source, used for dates only). Wikipédia (FR), rev. 8 Oct 2026.fr.wikipedia.org/wiki/Université_d
Cite this chapter
Cameroon Steel (2026). Domestic steel saves foreign exchange only when it competes at border prices. White paper 09, chapter 5: Employment: about 500 direct jobs in Phase 1 and 1,100 at full capacity, with a wide range beyond. CS-WP-09. https://www.cameroon-steel.com/en/library/economics-of-domestic-steel/employment/
Source