White paper 09 · Chapter 9
An illustrative footprint of a phased 1 Mtpa works: the foreign-exchange gain grows with domestic iron
This chapter combines the planned volumes of Cameroon Steel’s reference configuration with sourced border prices to estimate, for illustration only, what a phased 1 Mtpa electric arc furnace works could mean for Cameroon’s foreign-exchange position. At full utilisation, the three planned phases would produce long products worth about 113 to 121 bn FCFA a year at border prices in Phase 1, 190 to 213 bn FCFA after Phase 2 and 390 to 455 bn FCFA at 1 Mtpa, between two and three times the 2025 chapter 72 import bill of 170.1 bn FCFA [F][G34][C05], illustrative. The foreign exchange actually retained in the country is a fraction of that value and depends above all on where the iron units come from: at 1 Mtpa, about 40 to 154 bn FCFA a year if scrap and hot briquetted iron are imported, 48 to 160 bn FCFA with domestic scrap at the RC-1 planning level of 30,000 tonnes a year, and 324 to 418 bn FCFA if the iron units are domestic, before any capital service or profit remittance, illustrative. On imported iron units, a domestic works saves about as much foreign exchange per tonne as today’s re-rollers of imported billets. National scrap is far too small to change that at this scale. The large gain comes with domestic iron, which for a works of 1 Mtpa means direct reduction.
In this chapter (7)
- 9.1 Method: planned volumes, market prices, and nothing from the balance sheet
- 9.2 Gross value: output worth up to 2.7 times the 2025 chapter 72 bill, from Phase 2 above the whole domestic market
- 9.3 Per tonne, the foreign exchange retained depends on the iron route, not on rolling
- 9.4 By phase, only domestic iron makes the works a large net foreign-exchange saver
- 9.5 Four adjustments would lower these figures, and one would raise them
- 9.6 Set against the macro aggregates, the effect ranges from marginal to material
- 9.7 The iron-unit pathway is what turns a steel project into an import-substitution programme
9.1 Method: planned volumes, market prices, and nothing from the balance sheet
The footprint uses only three kinds of input, each with its status shown (full assumptions in Annex A).
Volumes are the planned and indicative finished output of RC-1: Phase 1, 300,000 tonnes a year of rebar (8 to 32 mm) and wire rod (5.5 to 12 mm); Phase 2, a further 200,000 tonnes of angles, channels and flats; Phase 3, a further 500,000 tonnes of H-beams, I-beams and heavy sections, for a total of 1 Mtpa [F]. Phase 1 has a nameplate capacity of 0.3 Mtpa and an expected sustained output of 270,000 to 300,000 tonnes a year. Its targets are works from the first quarter of 2029, a first heat in the second half of 2030 and ramp-up through 2031; Phase 2 is indicative for 2032 to 2034 and Phase 3 after 2034, subject to market and financing; a direct-reduction module for Cameroonian ore is indicative after 2034, subject to ore quality, gas supply and approvals [F]. The footprint assumes full utilisation of each phase at nameplate, which makes it an upper bound for any given year.
Prices are border prices delivered to Cameroon (cost, insurance and freight, CIF) at October 2026 market levels: US$660 to 710 per tonne for rebar and wire rod, from rebar at US$620 to 630 free on board plus US$40 to 80 freight [G34]; US$680 to 800 for light sections and US$700 to 850 for heavy sections, assumptions anchored on the rebar price and on the higher unit values of section imports recorded by Comtrade [G34][C06]. Imported metallics are priced at US$400 to 445 per tonne delivered [G34][W10]. Values are converted at 570 FCFA per US dollar [W13].
Imported content per tonne distinguishes four iron-unit routes (Table 9.1). The status quo is re-rolling imported billets, as Cameroon’s mills do now. Scenario S1 melts imported scrap and HBI. Scenario S2 uses domestic scrap at the RC-1 planning level, 30,000 tonnes a year within a range of 0 to 60,000, at every phase, and imports the rest of the charge [F]. That level is bounded by the only quantified estimate of national scrap arising, 53,000 to 62,000 tonnes a year in 2006, most of which already feeds existing mills [C42][C38]. Each tonne of domestic scrap replaces a tonne of imported metallics worth US$400 to 445; because the tonnage does not grow with the works, its share of the charge falls from about 8% in Phase 1 to about 2.5% at 1 Mtpa. A share of 40% domestic scrap, the coverage that local scrap provides to existing mills [C38], is shown only as a per-tonne sensitivity in Figure 9.2. It is not available at the works’ scale on current evidence: 40% of the charge would be about 145,000 tonnes a year in Phase 1 and about 484,000 tonnes at 1 Mtpa, between two and nine times the national arising [F][C42], derived. Scenario S3 uses domestic iron units throughout, as would be the case with domestic scrap and direct reduced iron made from Cameroonian ore and gas; its remaining imported content, consumables and spares, is assumed at US$65 to 115 per tonne.
9.2 Gross value: output worth up to 2.7 times the 2025 chapter 72 bill, from Phase 2 above the whole domestic market
At October 2026 border prices and full utilisation, Phase 1 output would be worth about US$198 to 213 million a year (113 to 121 bn FCFA); the first two phases together about US$334 to 373 million (190 to 213 bn FCFA); and the full 1 Mtpa about US$684 to 798 million (390 to 455 bn FCFA) [F][G34][W13], illustrative. At full capacity, that is 2.3 to 2.7 times Cameroon’s 2025 chapter 72 import bill [C05], derived.
The volumes put the market question plainly (Figure 9.1). Phase 1, at 300,000 tonnes, is below Cameroon’s apparent steel use of about 450,000 tonnes a year [C40] but above domestic rebar demand of about 180,000 tonnes, which existing mills already supply from about 627,000 tonnes of capacity [C30]. From Phase 2, the planned output of 500,000 tonnes exceeds both Cameroon’s entire chapter 72 imports in 2025 (412,000 tonnes) and its apparent steel use [C05][C40]. At 1 Mtpa, at least half of the output would have to be exported or would displace other domestic producers. The foreign-exchange arithmetic must therefore distinguish output that replaces imports, output that is exported, and output that merely displaces other domestic production.
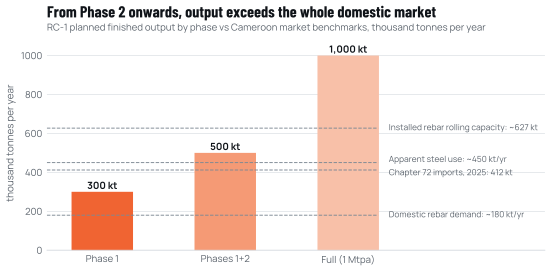
Source: Cameroon Steel RC-1 [F] (Phase 1 planned; later phases indicative); INS 2025 [C05]; Camer.be, 1 October 2026 [C40]; Cameroon Tribune, 11 May 2026 [C30].
9.3 Per tonne, the foreign exchange retained depends on the iron route, not on rolling
Figure 9.2 shows the foreign exchange retained per tonne of rebar under the four routes and one sensitivity, defined as the CIF value of the rebar that the domestic product replaces (or the export it makes possible) minus the foreign exchange spent on imported inputs.
- Status quo, re-rolling imported billets. About 1.04 tonnes of billet at US$505 to 560 delivered, plus imported rolls, spares and consumables, give imported content of about US$540 to 612 per tonne of rebar. The foreign exchange retained is US$48 to 170 per tonne, 7% to 24% of the CIF value [G34][F], illustrative.
- S1, melting imported scrap and HBI. About 1.21 tonnes of metallics at US$400 to 445, plus imported electrodes, alloys, refractories and spares, give imported content of about US$529 to 613. The foreign exchange retained is US$47 to 181 per tonne, 7% to 26% of the CIF value: essentially the same as the status quo [G34][W10][F], illustrative.
- S2, domestic scrap at the planning level. In Phase 1, 30,000 tonnes of domestic scrap amount to about 0.1 tonne per tonne of rebar, about 8% of the charge. Imported content falls to about US$489 to 568, and the foreign exchange retained rises to US$92 to 221 per tonne, 14% to 31% of the CIF value [F], illustrative.
- Sensitivity: 40% domestic scrap. Imported content would fall to US$335 to 398 and the foreign exchange retained would rise to US$262 to 375 per tonne, 40% to 53% of the CIF value, illustrative. National scrap cannot supply this share at the works’ scale.
- S3, domestic iron units. Imported content falls to US$65 to 115, and the foreign exchange retained rises to US$545 to 645 per tonne, 83% to 91% of the CIF value, illustrative.
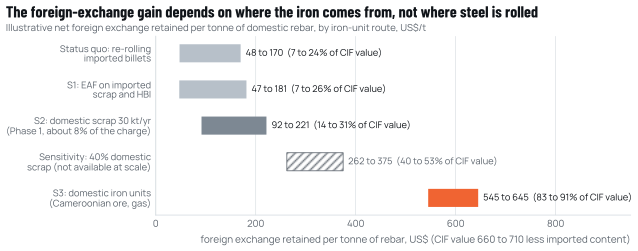
Source: illustrative calculation by Cameroon Steel; prices AISU, 3 October 2026 [G34] and SteelOrbis, 15 May 2026 [W10]; input coefficients and domestic scrap RC-1 [F]; scrap arising [C42]; assumptions in Annex A.
The comparison between the status quo and S1 is the most important result of this paper. Replacing rebar rolled in Douala from imported billets with rebar melted in Kribi from imported scrap and HBI saves almost no foreign exchange per tonne: the country stops importing billets and starts importing the scrap and HBI to make them. Using the midpoints of the ranges, the gain per tonne relative to today is about US$50 with domestic scrap at the Phase 1 planning level, about US$210 in the 40% sensitivity, which national scrap cannot supply at this scale, and about US$485 with domestic iron units, illustrative. Where the iron comes from matters more than where the steel is rolled.
For products not made in Cameroon, the comparison is different. Sections replace imports rather than domestic production, so even on imported iron units their foreign-exchange saving is real: about US$90 to 320 per tonne of heavy sections in S1, rising with domestic iron [C06], illustrative. This is why the phasing of products matters as much as the phasing of iron.
9.4 By phase, only domestic iron makes the works a large net foreign-exchange saver
Figure 9.3 and Table 9.1 aggregate the per-tonne results over the planned volumes, on the assumption that all output either replaces imports into Cameroon or is exported in a way that saves foreign exchange for the CEMAC union (Chapter 8). The results are annual, at full utilisation and before capital service.
In Phase 1, the foreign exchange retained would be about 8 to 31 bn FCFA a year in S1, 16 to 38 bn FCFA in S2 and 93 to 110 bn FCFA in S3, illustrative. After Phase 2, the ranges become 16 to 62, 23 to 69 and 158 to 194 bn FCFA. At 1 Mtpa, they become 40 to 154, 48 to 160 and 324 to 418 bn FCFA a year, illustrative. Domestic scrap at the planning level adds about 7 bn FCFA a year to S1 at every phase (6.8 to 7.6), and 0 to 15 bn FCFA across its range of 0 to 60,000 tonnes [F], illustrative. Against the 2025 chapter 72 import bill of 170.1 bn FCFA [C05], a full-capacity works on imported iron units would save the equivalent of 24% to 91% of that bill; with domestic scrap at the planning level, 28% to 94%; with domestic iron units, 190% to 246%, derived.
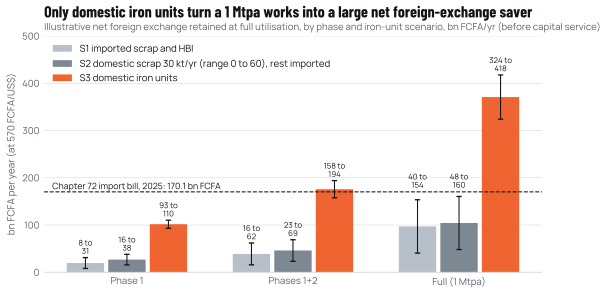
Source: illustrative calculation by Cameroon Steel; volumes and domestic scrap RC-1 [F]; scrap arising [C42]; prices AISU [G34] and SteelOrbis [W10]; 2025 import bill INS [C05]; assumptions in Annex A.
Table 9.1 Illustrative annual economic footprint of the RC-1 phases at full utilisation (October 2026 prices; before capital service)
| Phase (status) | Finished output | Gross value at border prices | Net foreign exchange retained, S1 imported metallics | S2, domestic scrap 30 kt/yr | S3, domestic iron units | S3 as share of 2025 chapter 72 bill |
|---|---|---|---|---|---|---|
| Phase 1 (planned) | 300 kt | 113 to 121 bn FCFA | 8 to 31 bn FCFA | 16 to 38 bn FCFA | 93 to 110 bn FCFA | 55% to 65% |
| Phases 1 and 2 (indicative) | 500 kt | 190 to 213 bn FCFA | 16 to 62 bn FCFA | 23 to 69 bn FCFA | 158 to 194 bn FCFA | 93% to 114% |
| Full, 1 Mtpa (indicative) | 1,000 kt | 390 to 455 bn FCFA | 40 to 154 bn FCFA | 48 to 160 bn FCFA | 324 to 418 bn FCFA | 190% to 246% |
| Memo: status quo route, per tonne of rebar | US$660 to 710 per t | US$48 to 170 per t retained by re-rolling imported billets |
Source: illustrative calculation by Cameroon Steel; volumes and domestic scrap RC-1 [F]; scrap arising [C42]; prices [G34][W10]; exchange rate [W13]; 2025 import bill [C05]. Ranges reflect price and input assumptions in Annex A; they are not forecasts. Across the domestic-scrap range of 0 to 60,000 tonnes a year, S2 spans 8 to 45, 16 to 76 and 40 to 167 bn FCFA by phase.
9.5 Four adjustments would lower these figures, and one would raise them
The figures above are upper bounds in four respects.
Exports earn free-on-board prices. Output that is exported earns the destination price minus freight, not the CIF price of the home market. With 40 to 80 US dollars of freight per tonne, the value of exported tonnes is 6% to 12% lower [W12], assumed.
Displacement of domestic producers saves nothing extra. Output that replaces rebar made by existing Cameroonian mills from imported billets saves only the difference between the routes in Figure 9.2. In S1, that difference is close to zero.
Capital service and remittances flow abroad. Debt service on foreign loans, dividends to foreign shareholders and the salaries of expatriate staff are foreign-exchange outflows. The 2025 incentive ordinance guarantees the free transfer of dividends, subject to CEMAC exchange regulation [W08]. This paper does not estimate them, because they depend on investment and financing figures it does not disclose, but they would reduce the net saving, particularly in the early years.
Construction imports equipment. The machinery, electrical equipment and steel structures of each phase are largely imported, a one-off foreign-exchange outflow during construction.
One factor would raise the figures: the scarcity value of foreign exchange. With pooled reserves at 4.2 months of imports and transfers rationed (Chapter 1), each dollar saved is worth more to the economy than its face value. The footprint values it at par.
9.6 Set against the macro aggregates, the effect ranges from marginal to material
Placed against the macroeconomic figures of Chapter 1, the illustrative results show why the iron-unit route matters for policy and not only for the project.
On imported iron units (S1), the foreign exchange retained at 1 Mtpa, 40 to 154 bn FCFA a year, would equal about 2% to 7% of Cameroon’s 2025 merchandise trade deficit of 2,145.2 bn FCFA and between about 0.6% and 2.4% of CEMAC’s pooled reserves at the end of 2025 [C05][P07], derived. That is useful, but it is of the same order as the saving already achieved by re-rolling imported billets, and part of it would flow back out as capital service.
With domestic iron units (S3), the figure of 324 to 418 bn FCFA a year would equal about 15% to 19% of the 2025 trade deficit and about 5% to 7% of the union’s end-2025 reserves [C05][P07], derived. At that scale a single industrial value chain would change the external accounts noticeably, in the way that the rise of gas-based steel changed Algeria’s steel trade balance within four years (Chapter 3) [A03].
Domestic scrap at the planning level (S2) changes these shares little: 48 to 160 bn FCFA a year at 1 Mtpa would equal about 2% to 8% of the 2025 trade deficit and about 0.8% to 2.5% of the union’s reserves [C05][P07], derived. Scrap collection can raise the saving per tonne, but the national pool is far too small to supply a works of this scale; at 1 Mtpa the large gain requires domestic DRI. Organising scrap collection remains worthwhile for the industry as a whole: it is cheaper and faster than building a direct-reduction plant, and existing mills already rely on local scrap for about 40% of their needs [C38].
9.7 The iron-unit pathway is what turns a steel project into an import-substitution programme
The footprint points to a clear sequencing logic, consistent with the RC-1 phasing [F].
Phase 1 (a billet melt shop with rebar and wire-rod mills) creates jobs, skills, a regional supply capability and a site. On imported iron units its foreign-exchange saving per tonne is about what a re-roller saves, and its rebar would largely compete with rebar already rolled in Cameroon from imported billets. It saves foreign exchange where its output displaces imports: merchant billets for re-rollers that import about 60% of their charge, wire rod, certified rebar in place of non-compliant bars, and exports to CEMAC neighbours that replace imports from outside the union [C06][C38]. Domestic scrap at the planning level adds about 7 bn FCFA a year.
Phases 2 and 3 (sections and heavy sections) replace imports of products not made in Cameroon and open export markets. Their foreign-exchange case holds even on imported iron, provided the products are competitive at border prices (Chapter 7).
The iron-unit step, a national scrap-collection effort that helps the whole industry but is small relative to a works of this scale, and later a direct-reduction module using Cameroonian ore and gas, is what multiplies the saving. It depends on conditions outside any single company: ore of a quality suitable for direct reduction, a long-term gas supply (about 9 billion cubic feet a year for 1 Mt of direct reduced iron, roughly 12% of 2025 national production [E04][F], derived), and the local-transformation obligations in mining conventions, which the 2023 Mining Code sets at a minimum of 15% [W09][O17].
The conclusion for public policy follows directly. If the objective is foreign exchange, the instruments of Chapter 10 should reward domestic iron units and products not made locally, and should not reward additional rolling of imported metal behind a closed border.
Sources cited in this chapter
Bracketed markers refer to these sources; the full list is in the annex. Full list of sources
- FCameroon Steel reference configuration RC-1 (planning estimate), edition 10 October 2026 (RC-1.1). Cameroon Steel, 10 Oct 2026.Cited by title and date
- G34Weekly steel prices (archive 40468). Arab Iron & Steel Union (AISU), 3 Oct 2026.aisusteel.org/en/archives/40468
- C06UN Comtrade public API: Cameroon (reporter 120), HS 72/73 and 6-digit lines, 2019-2023. UN Statistics Division.comtradeapi.un.org/public/v1/preview/C/A/HS?reporterCode=120&period=20…
- W10Global HBI market bullish amid tight supply, ex-Libya tender closure to give further direction. SteelOrbis, 15 May 2026.steelorbis.com/steel-prices/steel-prices-market-analyses/scrap-and-raw…
- W13Euro foreign exchange reference rates, US dollar, monthly averages (series EXR.M.USD.EUR.SP00.A). European Central Bank.data-api.ecb.europa.eu/service/data/EXR/M.USD.EUR.SP00.A
- C42Bidoung J., Fomethe A., Yantio G., Melo U., La récupération et le recyclage des déchets ferromagnétiques: analyse de la situation au Cameroun (Déchets, Revue francophone d’écologie industrielle n°48). ENSP Yaoundé / MIPROMALO, Q4 2007.eid.episciences.org/7942/pdf
- C38Cameroun: le groupe Prometal décroche 26 milliards FCFA auprès d’Afreximbank…. Sikafinance, 30 Sep 2026.sikafinance.com/marches/cameroun-le-groupe-prometal-decroche-26-millia…
- C05Évolution du commerce extérieur en 2025 (version provisoire). INS Cameroun, Feb 2026 (posted 1 Apr 2026).ins-cameroun.cm/wp-content/uploads/2026/04/Note-sur-le-commerce-exteri…
- C40Cameroun: Prometal décroche 26,2 milliards FCFA d’Afreximbank. Camer.be, 1 Oct 2026.camer.be/actualites/economie/cameroun-prometal-decroche-262-milliards-…
- C30Production: les acteurs en présence. Cameroon Tribune, 11 May 2026.cameroon-tribune.cm/article.html/76600/fr.html/details_2
- W12At 11.4 per cent of the value of imports, African countries paid more for international transport than any other region (Review of Maritime Transport 2015). UNCTAD, 2015.unctad.org/press-material/114-cent-value-imports-african-countries-pai…
- W08Ordonnance n° 2025/002 du 18 juillet 2025 fixant les incitations à l’investissement en République du Cameroun (certified copy). Presidency of the Republic, copy hosted by LEGECAM, 18 Jul 2025.legecam.cm/wp-content/uploads/2025/08/ordonnance_n_2025_002_du_18_07_2…
- P07Zone Cémac: la BEAC annonce un ralentissement de croissance à 2,4%. AllAfrica (Les Dépêches de Brazzaville), 17 Dec 2025.fr.allafrica.com/stories/202512170629.html
- A03Protecting the steel market: how it’s done in North Africa. GMK Center, 2 Sep 2026.gmk.center/en/posts/protecting-the-steel-market-how-it-s-done-in-north…
- E04Données pétrolières 2025. SNH, posted Jun 2026.snh.cm/wp-content/uploads/2026/06/Donnees-petrolieres-2025.pdf
- W09Loi n° 2023/014 du 19 décembre 2023 portant Code minier (Article 40(4), local transformation). Republic of Cameroon, copy on FAOLEX, 19 Dec 2023.faolex.fao.org/docs/pdf/cmr223180.pdf
- O17Cameroon Mining Company confirme l’entrée du projet Mbalam dans sa phase irréversible d’exécution. Camer.be via AllAfrica, 12 Dec 2025.fr.allafrica.com/stories/202512120475.html
Cite this chapter
Cameroon Steel (2026). Domestic steel saves foreign exchange only when it competes at border prices. White paper 09, chapter 9: An illustrative footprint of a phased 1 Mtpa works: the foreign-exchange gain grows with domestic iron. CS-WP-09. https://www.cameroon-steel.com/en/library/economics-of-domestic-steel/economic-footprint/
Source