白皮书09 · 第1章 · 中文摘要
喀麦隆宏观背景:增长平稳,外部缺口扩大,缓冲空间有限
喀麦隆经济保持每年3%至4%的平稳增长,但外部状况已经恶化:外汇因储备偏低而具有稀缺价值,财政无力长期供养缺乏竞争力的产业,而国内钢铁市场规模有限。
本页为本章中文摘要;英文全文附于其后,可展开阅读。
2025年喀麦隆实际GDP增长3.5%,建筑业实际增长4.3%,快于整体经济[C09]。同年商品贸易逆差扩大22.8%,达21452亿中非法郎;协调制度第72和73章钢铁及其制品进口合计2781亿中非法郎,占逆差的13.0%,2023年和2024年分别为14.8%和13.8%[C05]。CEMAC共同外汇储备由2024年末的72950亿中非法郎降至2025年末的63773亿中非法郎,仅相当于4.2个月进口,超过5000万中非法郎的对外转账须经中部非洲国家银行(BEAC)批准[P06][P07][P10]。国际货币基金组织估计2025年经常账户逆差为GDP的5.2%,公共债务为GDP的40.3%,债务困境风险为“高”[P09][P32]。制造业增加值约占GDP的13.3%,远低于国家发展战略(SND30)提出的2030年25%目标[C09][P13]。
由此得出四点含义:持久减少的每一美元进口都高于其面值;外汇节省必须按净额计算;保护的成本由消费者或财政承担;国内表观钢材消费仅约45万吨/年,年产100万吨的钢厂满产时必须以出口为主[C40]。
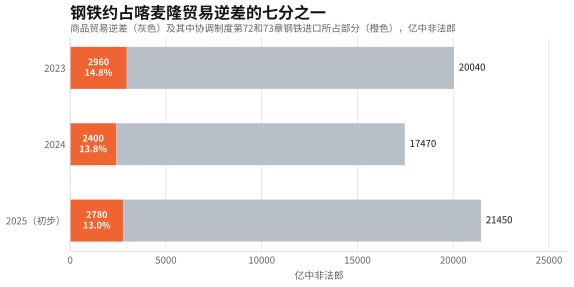
资料来源:喀麦隆国家统计局2023年、2024年和2025年(初步)对外贸易简报[C03][C04][C05];占比由Cameroon Steel计算。
英文全文 11分钟 · 2508词Cameroon’s macro context: steady growth, a widening external gap and thin buffers
Cameroon is growing at a steady 3 to 4% a year, but its external position has weakened: the merchandise trade deficit widened by 22.8% to 2,145.2 bn FCFA in 2025, the current-account deficit is projected above 5% of GDP, and the reserves that the six CEMAC states hold in common fell to 4.2 months of imports at the end of 2025 [C05][P09][P07]. Hydrocarbon revenue is set to fall after the July 2026 departure of the floating LNG plant, and the IMF rates the country at high risk of debt distress [E09][P32]. In this setting, any activity that durably replaces imports or earns foreign exchange has macroeconomic value beyond its own accounts. The same setting also leaves little fiscal room to pay for industries that cannot stand on their own. This chapter sets out the numbers on which the rest of the paper builds.
1.1 Growth is steady at 3 to 4%, and construction grows faster than the economy
Cameroon’s real gross domestic product grew by 3.5% in 2025, according to the national accounts published by the Institut National de la Statistique (INS) in August 2026, after 3.5% in 2024 and 3.3% in 2023 [C09]. Nominal GDP reached 34,474.0 bn FCFA in 2025, up from 32,316.2 bn FCFA in 2024 [C09], or about US$59 bn at 2025 exchange rates [C10]. The International Monetary Fund’s April 2026 World Economic Outlook carried a slightly lower 2025 estimate of 3.1% and projects 3.3% in 2026, 3.8% in 2027 and 4.2% in 2028 [C10]. The World Bank’s September 2026 country update estimates growth of 3.4% in 2025 and an average of 3.7% over 2026 to 2028 [C12]. In its October 2026 post-financing assessment, IMF staff retained 3.5% for 2025 but noted that "prospects are weakening for 2026", mainly because of hydrocarbons [P32]. Over the medium term, the IMF expects growth to approach 4.6% "as mining diversification materializes" [P09].
Two features of this growth matter for steel. First, construction grows faster than the economy as a whole. The value added of buildings and public works (bâtiments et travaux publics, BTP) rose by 4.3% in real terms in both 2024 and 2025, after 2.3% in 2023, and amounted to 1,991.1 bn FCFA in 2025, or about 5.8% of GDP [C09]. Construction is the main market for long steel products: reinforcing bar (rebar), wire rod and the sections used in frames, sheds and bridges. Second, investment is modest. Gross fixed capital formation rose by only 1.9% in 2025, led by private investment while public investment slowed [C09]. The 2026 State budget of 8,816.4 bn FCFA, 14% larger than in 2025, allocates 2,026.3 bn FCFA to public investment and assumes 4.3% growth [C16].
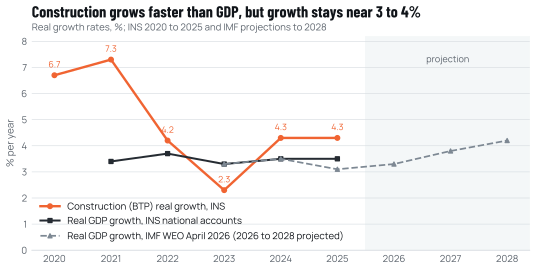
Source: INS, Les Comptes Nationaux de 2025 (August 2026) [C09]; IMF, World Economic Outlook database, April 2026 [C10].
The structural pull on steel comes from urbanisation and housing. The World Bank estimates that 55.7% of Cameroonians lived in towns in 2025 [C13]. The Centre for Affordable Housing Finance in Africa puts the national housing deficit at 1.8 to 2.0 million units, with annual demand of about 300,000 units against about 150,000 supplied [C15]. Each unit, road, bridge and port extension consumes rebar and sections. One caution applies to every per-capita figure in this paper: the World Bank and the IMF estimate the population at 29.88 million in 2025 [C13], but the provisional results of the fourth general population census (RGPH4), released in October 2026, enumerate 22.7 million people, about 24% fewer [C14]. Until the census is final, per-capita indicators should be read as ranges.
1.2 The trade deficit widened to 2,145 bn FCFA in 2025, and steel is one-seventh of it
Cameroon imported goods worth 5,229.2 bn FCFA in 2025, 4.6% more than in 2024, and its merchandise trade deficit widened by 22.8% to 2,145.2 bn FCFA [C05]. Exports covered only 59.0% of imports [C05]. Excluding crude oil, the deficit reached 2,850.9 bn FCFA [C05]: the non-oil economy imports far more than it sells abroad, and oil exports finance a large part of the gap. China supplied 22.2% of Cameroon’s imports in 2024 [C04].
Iron and steel are a significant and stable part of the deficit. Imports under chapter 72 of the Harmonized System (iron and steel) and chapter 73 (articles of iron or steel) together amounted to 278.1 bn FCFA in 2025, equal to 5.3% of all imports and 13.0% of the trade deficit [C05]. The share was 14.8% in 2023 and 13.8% in 2024 (Figure 1.2). Chapter 72 alone, which covers the semi-finished and finished steel that a steelworks could make, cost 170.1 bn FCFA in 2025, or 7.9% of the deficit [C05]. Chapter 2 examines this bill in detail.
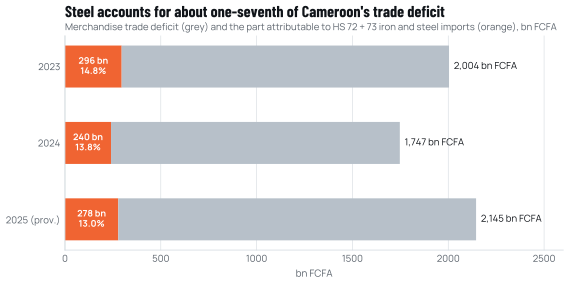
Source: INS foreign-trade notes for 2023, 2024 and 2025 (provisional) [C03][C04][C05]; shares calculated by Cameroon Steel.
The current account tells the same story with services and income included. The IMF estimates the current-account deficit at 3.3% of GDP in 2024 and 5.2% in 2025, and projects 5.4% for 2026 [P09]. A deficit of that size must be financed by capital inflows or by drawing on reserves. For a member of a monetary union, that second option has a particular meaning.
1.3 CEMAC’s pooled reserves fell to 4.2 months of imports, and the rules on foreign exchange tightened
Cameroon does not hold its own foreign-exchange reserves in the usual sense. It shares a currency, the CFA franc of Central Africa (FCFA), and a central bank, the Bank of Central African States (BEAC), with Gabon, the Republic of Congo, Chad, the Central African Republic and Equatorial Guinea. The FCFA is pegged to the euro at 655.957 FCFA per euro; its rate against the US dollar floats with the euro and averaged about 570 FCFA per dollar in September 2026 [W13]. The peg is backed by the union’s pooled reserves.
Those reserves fell from 7,295 bn FCFA at the end of 2024 to 6,377.3 bn FCFA at the end of 2025, equal to 4.2 months of imports [P06][P07]. In early 2025 the BEAC had still projected 4.8 months for 2025 and 5.3 months for 2026 [P08]. The central bank raised its main tender rate to 4.75% in December 2025 [P07]. Cameroon, as the largest economy and the largest importer in the union, weighs heavily in that result.
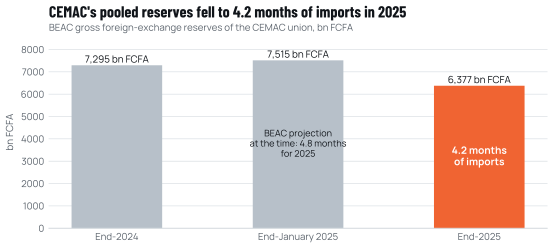
Source: BEAC statements reported by Gabon Media Time (2 January 2026) [P06], Les Dépêches de Brazzaville via AllAfrica (17 December 2025) [P07] and EcoMatin (1 April 2025) [P08].
The regulatory response has been to ration foreign exchange more tightly rather than to devalue. Under CEMAC Regulation No. 02/18 of 21 December 2018, transfers above 50 million FCFA require BEAC authorisation [P10]. Cameroon’s 2025 Finance Law (Article 8) removed customs facilities from imported goods that have locally made equivalents, with the explicit objective of limiting outflows of foreign currency (limiter la sortie des devises), subject to exceptions for the Economic Partnership Agreements with the EU and UK, the AfCFTA, CEMAC and ECCAS trade, and certified shortages [P18]. The 2026 Finance Law went further, prohibiting purchases from foreign suppliers without an effective transfer of funds [P11]. These measures show that foreign exchange is now a binding constraint in policy, not only in the statistics.
1.4 Public finances have little room for costly protection
Cameroon’s public finances have improved, but they offer limited room for subsidies, tax exemptions or high-cost protection. The IMF’s 2026 Article IV consultation, concluded by its Executive Board in March 2026, put public debt at 43.4% of GDP in 2024, 40.3% in 2025 and a projected 39.6% in 2026, and noted fiscal slippage in 2025: the non-oil primary deficit reached 2.6% of GDP against a target of 1.4% [P09][C11]. The World Bank estimates public and publicly guaranteed debt at 42.9% of GDP in March 2026 [C12]. Both institutions rate the overall risk of debt distress as high [P32][C12].
Cameroon completed its IMF-supported programme in 2025. The Extended Credit Facility and Extended Fund Facility arrangements approved in July 2021 (SDR 483 million, extended in December 2023) and the Resilience and Sustainability Facility of January 2024 (SDR 138 million) reached their eighth and third reviews respectively in July 2025 [P34]. The country is now under a post-financing assessment, with the next Board discussion expected in December 2026 [P32]. The IMF’s consistent message has been to raise non-oil revenue, contain tax expenditures and improve the governance of State-owned enterprises [P09].
Hydrocarbon revenue is about to fall. The Hilli Episeyo floating liquefaction vessel left Kribi in July 2026 at the end of its charter; press reports projected a loss of gas revenue of 235 bn FCFA over 2026 and 2027 [E08][E09]. Extractive value added already fell by 6.1% in 2025, with hydrocarbons down 6.6% [C09]. Any new incentive regime for industry, including the one examined in Chapter 6, will therefore be judged by what it costs the budget as well as by what it builds.
1.5 Manufacturing is stuck near 13% of GDP, against a 25% target for 2030
The National Development Strategy 2020 to 2030 (SND30) sets a target of 25% of GDP for manufacturing value added by 2030 and names mines, métallurgie et sidérurgie (mining, metallurgy and steel) among nine priority industrial sub-sectors [P13]. Its doctrine is explicit: "accélérer l’import-substitution tout en densifiant les exportations", accelerating import substitution while expanding exports [P13]. On INS data, manufacturing value added was about 13.3% of GDP in 2025 (agro-food industries 2,505.1 bn FCFA and other manufacturing 2,085.8 bn FCFA) [C09]; the World Bank’s series, on a different basis, shows 14.6% [P12]. The secondary sector as a whole, including extraction, energy and construction, accounted for about 22.7% of GDP [C09]. On either measure, the economy is roughly halfway to its 2030 manufacturing target with four years left.
A single industrial complex will not close that gap. Moving the manufacturing share from 13% to 25% of a 34,474 bn FCFA economy would require roughly 4,000 bn FCFA of additional manufacturing value added at 2025 scale [C09], more than twenty times the 2025 chapter 72 import bill. What industrial projects can do is add value in sectors with strong links to the rest of the economy, and steel is one of the few sectors in which a single works can be large relative to the national market. Chapter 4 quantifies those links.
Table 1.1 Cameroon macroeconomic dashboard, latest data at 10 October 2026
| Indicator | Value | Period | Source |
|---|---|---|---|
| Real GDP growth (INS / IMF) | 3.5% / 3.1% | 2025 | [C09][C10] |
| IMF growth projection | 3.3% (2026), 3.8% (2027), 4.2% (2028) | 2026 to 2028 | [C10] |
| Nominal GDP | 34,474.0 bn FCFA (about US$59 bn) | 2025 | [C09][C10] |
| Construction (BTP) real growth; share of GDP | 4.3%; 5.8% | 2025 | [C09] |
| Inflation (IMF) | 3.4% | 2025 | [C10] |
| Merchandise imports | 5,229.2 bn FCFA (+4.6%) | 2025 | [C05] |
| Merchandise trade deficit; export cover | 2,145.2 bn FCFA (+22.8%); 59.0% | 2025 | [C05] |
| Trade deficit excluding crude oil | 2,850.9 bn FCFA | 2025 | [C05] |
| Iron and steel (HS 72 + 73) imports; share of deficit | 278.1 bn FCFA; 13.0% | 2025 | [C05], derived |
| Current-account balance | minus 5.2% of GDP (minus 5.4% projected 2026) | 2025 | [P09] |
| CEMAC pooled reserves | 6,377.3 bn FCFA = 4.2 months of imports | end-2025 | [P06][P07] |
| BEAC main tender rate | 4.75% | from Dec 2025 | [P07] |
| Public debt | 40.3% of GDP (IMF); high risk of debt distress | 2025 | [P09][P32] |
| Public investment budget | 2,026.3 bn FCFA | 2026 | [C16] |
| Manufacturing value added | 13.3% of GDP (INS basis) vs 25% SND30 target | 2025 / 2030 | [C09][P13] |
| Population (World Bank / RGPH4 provisional) | 29.88 m / 22.7 m | 2025 / 2026 | [C13][C14] |
| Urbanisation; housing deficit | 55.7%; 1.8 to 2.0 m units | 2025; 2024 | [C13][C15] |
Source: as listed in the table; derived values are Cameroon Steel calculations from the sources shown.
1.6 What the macro setting implies for a domestic steel industry
Four implications follow, and they frame the rest of the paper.
First, foreign exchange has a scarcity value. With pooled reserves at 4.2 months of imports and administrative rationing of transfers, a dollar of imports durably avoided, or of exports durably earned, is worth more to the economy than its face value. Economists call this a shadow price of foreign exchange; this paper does not estimate it, but it explains why governments in the region treat import substitution as a policy objective in its own right [P18][P13].
Second, the saving must be net. A plant that replaces imported steel with domestic steel made from imported scrap, imported direct reduced iron and imported electrodes, and that services foreign debt and pays foreign dividends, saves much less than the value of the steel it sells. Chapter 9 shows that the net saving per tonne can range from under 10% to over 80% of the import value, depending above all on where the iron units come from.
Third, the budget cannot carry an uncompetitive industry. Protection is paid for either by consumers, through higher prices, or by the budget, through forgone customs revenue and tax exemptions. With the IMF pressing for higher non-oil revenue and lower tax expenditures [P09], the State’s interest lies in an industry that becomes competitive at border prices, not in one that depends on permanent protection. Chapters 3, 6 and 7 develop this point.
Fourth, demand is growing but the market is small. Construction is growing at about 4% a year and housing needs are large [C09][C15], yet Cameroon’s apparent steel use is only about 450,000 tonnes a year [C40]. A works designed for 1 million tonnes a year must therefore plan to export most of its output at full capacity, which makes regional trade rules and export competitiveness central to its economics (Chapter 8).
Other sources cited in the English text
- C10World Economic Outlook DataMapper API (CMR: NGDP_RPCH, NGDPD, PCPIPCH). IMF, Apr 2026 WEO.imf.org/external/datamapper/api/v1/NGDP_RPCH/CMR
- C12Cameroon Overview. World Bank, updated Sep 2026.worldbank.org/en/country/cameroon/overview
- C16Budget 2026: 8 816,4 milliards FCFA…. MINFI, 26 Nov 2025.minfi.gov.cm/budget-2026-8-8164-milliards-fcfa-pour-consolider-la-stab…
- C13WDI API: SP.POP.TOTL; SP.URB.TOTL.IN.ZS (CMR). World Bank, updated 8 Oct 2026.api.worldbank.org/v2/country/CMR/indicator/SP.POP.TOTL?format=json
- C152024 Housing Finance Yearbook: Cameroon profile. Centre for Affordable Housing Finance in Africa (CAHF), Jan 2024 (PDF Mar 2025).housingfinanceafrica.org/wp-content/uploads/2025/03/CAMEROON.pdf
- C14Cameroun: bouclage du 4e RGPH, 22,7 millions d’habitants recensés. Journal du Cameroun, 5 Oct 2026.fr.journalducameroun.com/cameroun-bouclage-du-4e-rgph-227-millions-dha…
- W13Euro foreign exchange reference rates, US dollar, monthly averages (series EXR.M.USD.EUR.SP00.A). European Central Bank.data-api.ecb.europa.eu/service/data/EXR/M.USD.EUR.SP00.A
- P08CEMAC: les réserves de change progressent de 9% à 7 515 milliards FCFA à fin janvier 2025. EcoMatin, 1 Apr 2025.ecomatin.net/cemac-les-reserves-de-change-progressent-de-9-a-7-515-mil…
- P18Innovations douanières de la Loi de Finances 2025. MINFI, Direction Générale des Douanes, Jan 2025.minfi.gov.cm/wp-content/uploads/2025/01/EXPOSE_DGD_LF_2025.pdf
- P11Cameroun: les principales innovations de la loi de finances pour 2026. Deloitte Société d’Avocats, 24 Mar 2026.blog.avocats.deloitte.fr/cameroun-les-principales-innovations-de-la-lo…
- C11Cameroon: 2026 Article IV Consultation, Staff Report. IMF, 3 Apr 2026.imf.org/en/publications/cr/issues/2026/04/03/cameroon-2026-article-iv-…
- P34IMF concludes 8th reviews under ECF and EFF and 3rd review under RSF (PR 25/265). IMF, 24 Jul 2025.imf.org/en/News/Articles/2025/07/24/pr-25265-cameroon-imf-concludes-8t…
- E08Golar, partners approve first vessel in Argentine gas export project. Rigzone, 6 May 2025.rigzone.com/news/golar_partners_approve_first_vessel_in_argentine_gas_…
- E09Le navire usine quitte le Cameroun, le gaz s’arrête. Camer.be, 9 Jul 2026.camer.be/93911/12:1/le-navire-usine-quitte-le-cameroun-le-gaz-sarrete-…
- P12WDI API: NV.IND.MANF.ZS; NV.IND.TOTL.ZS (CMR). World Bank, upd. 8 Oct 2026.api.worldbank.org/v2/country/CMR/indicator/NV.IND.MANF.ZS?format=json
本章引用的资料来源
方括号内的标记对应以下来源(按原文语言列出),完整列表见附录。 完整来源列表
- C09Les Comptes Nationaux de 2025. INS Cameroun,2026年8月(发布:2026年9月2日).ins-cameroun.cm/wp-content/uploads/2026/09/Comptes_Nationaux_2025_FR_V…
- C05Évolution du commerce extérieur en 2025 (version provisoire). INS Cameroun,2026年2月(发布:2026年4月1日).ins-cameroun.cm/wp-content/uploads/2026/04/Note-sur-le-commerce-exteri…
- P06CEMAC: après le repli de 2025, la BEAC table sur un redressement progressif des réserves de change. Gabon Media Time,2026年1月2日.gabonmediatime.com/cemac-apres-le-repli-de-2025-la-beac-table-sur-un-r…
- P07Zone Cémac: la BEAC annonce un ralentissement de croissance à 2,4%. AllAfrica (Les Dépêches de Brazzaville),2025年12月17日.fr.allafrica.com/stories/202512170629.html
- P102024 Investment Climate Statements: Cameroon. US Department of State,2024年.state.gov/reports/2024-investment-climate-statements/cameroon/
- P09IMF Executive Board concludes 2026 Article IV consultation with Cameroon (PR 26/096). IMF,2026年3月30日.imf.org/en/news/articles/2026/03/30/pr-26096-cameroon-imf-executive-bo…
- P32IMF staff concludes Post-Financing Assessment mission to Cameroon (PR 26/314). IMF,2026年10月1日.imf.org/en/news/articles/2026/10/01/pr26314-imf-staff-concludes-assesm…
- P13Stratégie Nationale de Développement 2020-2030 (SND30). Republic of Cameroon / MINEPAT (hosted by FAOLEX),2020年.faolex.fao.org/docs/pdf/cmr211554.pdf
- C40Cameroun: Prometal décroche 26,2 milliards FCFA d’Afreximbank. Camer.be,2026年10月1日.camer.be/actualites/economie/cameroun-prometal-decroche-262-milliards-…
- C03Commerce extérieur du Cameroun en 2023. INS Cameroun,2024年4月.ins-cameroun.cm/wp-content/uploads/2025/07/Note-sur-le-Commerce-Exteri…
- C04Évolution du commerce extérieur en 2024. INS Cameroun,2025年8月.ins-cameroun.cm/wp-content/uploads/2025/12/Commext_2024_FR_Edite-final…
引用本章
Cameroon Steel(2026)。只有在边境价格上具备竞争力,国内钢铁才能节省外汇(中文摘要版)。白皮书09,第1章:喀麦隆宏观背景:增长平稳,外部缺口扩大,缓冲空间有限。CS-WP-09。https://www.cameroon-steel.com/zh/library/economics-of-domestic-steel/macro-context/
来源