白皮书02 · 第7章 · 中文摘要
钢铁龙头企业使克里比工业区成为自我供给的产业集群
钢铁厂很少是工业区内最大的雇主,却往往是使其他企业得以立足的业务。若将克里比港综合工业区设计为让副产品、工业气体和技术服务在相邻地块之间完成交换,而不必跨越全国,这将是提升每家入驻企业竞争力成本最低的途径之一。
本页为本章中文摘要;英文全文附于其后,可展开阅读。
按Cameroon Steel的指示性测算,一座年产100万吨的钢铁厂每年产生约18.5万吨副产品,其中钢渣约14.9万吨、电炉粉尘约1.6万吨,并需要约3700万标准立方米氧气[S112]。世界钢铁协会估计,钢铁业每2个就业岗位可带动供应链约13个岗位[S107]。克里比已具备消纳钢渣的水泥产业:年产100万吨的CIMPOR水泥厂于2024年7月19日由总理主持落成[S35],另一座年产100万吨水泥厂的修订投资协议于2026年2月19日签署[S37];喀麦隆2025年熟料进口约310万吨,较2024年增长约20%[S93]。废钢是区域内最稀缺的含铁原料:现有钢厂约60%的金属料以钢坯形式进口,本地废钢仅能满足行业约40%的需求[S98]。下游方面,喀麦隆2023年进口钢结构约5800万美元,进口钢坯及其他半成品16.14万吨、价值1.517亿美元[S94],为最大单项钢材进口;炼钢车间可向现有轧钢企业供应商品钢坯,使产量替代进口而非加剧已饱和的钢筋市场(白皮书04第9章)。就业方面,单一企业首期约有500个直接岗位和约1000个间接岗位,满产时约1100个直接岗位[S112]。
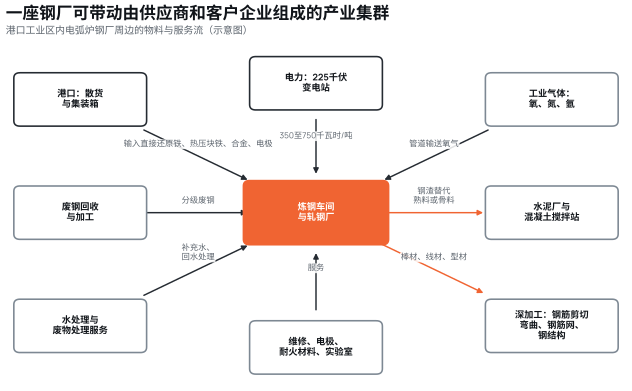
对KPIZ S.A.而言,集群不会仅因地理邻近而形成:主体规划应将钢铁集群紧邻散货泊位和高压变电站布置,钢渣场和制气厂紧邻钢厂,水泥厂位于钢渣场的输送带距离之内;在分配地块前预留管道和输送带走廊;建立副产品交换登记;并由KPIZ S.A.统一招标实验室、培训、消防和危险废物管理等共享服务。对投资者而言,钢渣可从处置成本转为道路骨料和水泥原料收入,钢筋加工和钢结构制造等劳动密集型业务适合喀麦隆中小企业,前提是其能够在本地赊购钢材。
英文全文 11分钟 · 2494词A steel anchor turns Kribi’s industrial zone into a cluster that feeds itself
A steel works is rarely the largest employer in an industrial zone, but it is often the business that makes others viable. It buys oxygen, electrodes, refractories, maintenance and transport; it sells slag to road builders and cement makers, scrap demand to collectors, and bars, rods and sections to fabricators. At 1 Mtpa a single works would generate about 185,000 t a year of by-products and need about 37 million Nm³ of oxygen [S112]. The world steel association estimates that every two jobs in steel support about thirteen in its supply chain [S107]. Kribi already hosts several of the industries a steel cluster would trade with, including a 1 Mt a year cement plant inaugurated in 2024 and a second 1 Mt a year cement project [S35][S37]. Designing the zone so that these exchanges happen across a fence rather than across a country is one of the cheapest ways to raise every tenant’s competitiveness.
7.1 Why clusters matter more in Central Africa
Industrial clusters reduce costs in three ways: tenants share infrastructure that none could justify alone; the by-products of one become the inputs of another; and suppliers locate nearby because there is enough demand to sustain them. These effects are strongest where the alternative is long and expensive. In Central Africa, a maintenance contractor, a gas supplier or a slag processor that is not on site may be a day’s drive or a sea voyage away. A steel plant that must import every service carries the cost of spares inventories, idle time and expatriate specialists. A cluster that can support local suppliers lowers those costs for every tenant.
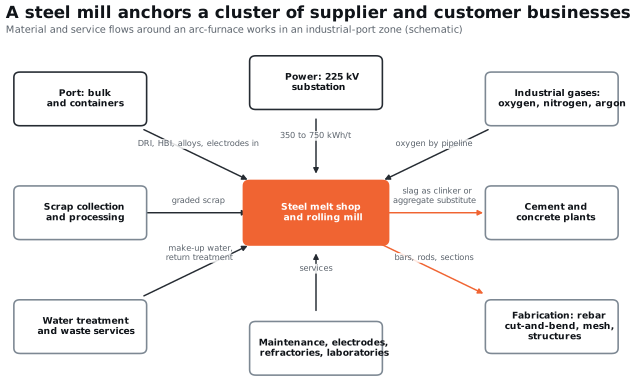
Figure 7.1 maps the main flows around an arc-furnace works in an industrial-port zone. None of them is speculative: each corresponds to a service that existing steel plants buy or a by-product that they sell. What varies is whether the counterpart is in the same zone.
Source: Cameroon Steel analysis; quantities in the text.
7.2 What Kribi’s first tenants show
The zone already has a cluster logic, built around raw materials that arrive or leave by sea. By May 2025, 53 companies had been authorised to settle in the industrial-port zone and industrial operators had invested about 400 bn FCFA there since 2018, in cocoa processing, cement, flour milling and logistics [S20]. By March 2026 about 300 ha were operational with more than 60 companies installed or installing [S03]. A cement plant and a flour mill are among the first tenants [S35][S20]; a bitumen plant with a small refinery has been allocated about 60 ha and received a refining licence in April 2026 [S36]; and an agro-industrial terminal for grain and oils was agreed in October 2026 [S19].
The common thread is that each of these businesses moves heavy, low-value material across the quay and adds value close to it. Steel fits that pattern better than almost any other industry: it imports iron units and consumables in bulk, exports heavy products, and creates by-products that its neighbours can use. It also brings something the existing tenants do not: a large, continuous demand for power, gases and technical services that justifies investment in them for the whole zone.
7.3 Slag: from waste to road stone and cement raw material
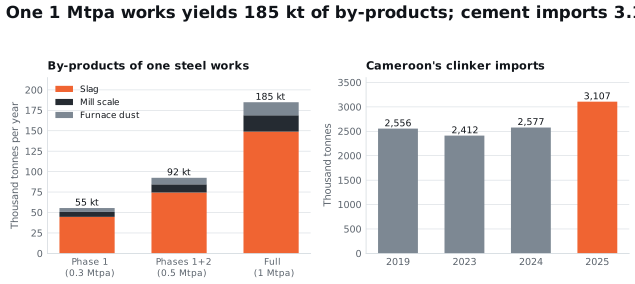
Electric arc furnaces produce about 110 to 180 kg of solid waste, mostly slag, per tonne of liquid steel [S75]. At 1 Mtpa, one works would produce about 149,000 t a year, and with mill scale and furnace dust its by-products would total about 185,000 t a year (Figure 7.2) [S112]. IFC’s guidelines for the sector note that steel slag can be sold for civil engineering, road construction and cement manufacture [S75]. In Europe, where steel slag markets are mature, about 72% of the 16.3 Mt of steelworks slag produced in 2018 was reported as recovered, with the balance stored or landfilled [S155].
Source: IFC solid-waste benchmark [S75]; dust planning range [S76][S112]; Cameroon Steel indicative balance [S112]; INS foreign-trade notes for 2019, 2023, 2024 and 2025 (provisional) [S93].
At Kribi, slag has two natural outlets. The first is construction aggregate. After crushing, screening and weathering to stabilise its volume, EAF slag makes a hard, skid-resistant aggregate for road bases and asphalt. The zone’s own internal roads, the reconstruction of the 110 km Édéa-Kribi road and the platforms of new tenants will need large quantities of aggregate over the next decade [S27][S18]. A slag-processing yard in the zone, producing certified aggregate, would turn a disposal cost into revenue and reduce quarrying.
The second outlet is cement. Cement plants can use steel slag as an iron-bearing component of their raw meal and, in some formulations, as a mineral addition. Granulated blast-furnace slag, the main cement substitute in Europe and Asia, comes from blast furnaces, which the Kribi platform is not expected to have; EAF slag’s role in cement is narrower. Even so, the proximity matters because Kribi has an unusually large cement presence for its size. The CIMPOR cement plant in the zone, with a capacity of 1 Mt a year, was inaugurated by the Prime Minister on 19 July 2024 as the first plant of the industrial-port zone [S35], and the Atlantic Group signed an amended investment agreement on 19 February 2026 for a second cement plant of 1 Mt a year at Kribi [S37].
Cameroon’s cement industry depends heavily on imported clinker, the intermediate product that is ground with gypsum and additions to make cement. Clinker imports rose to about 3.1 Mt in 2025, up about 20% on 2024 (Figure 7.2) [S93], and Nigerian producers alone exported about 1 Mt of clinker to Cameroon and Ghana in 2025 [S105]. Every tonne of mineral addition that replaces clinker in the cement mix reduces imports and the carbon footprint of cement. Steel slag will not solve the clinker deficit, but a cluster in which cement plants and steel plants share raw-material handling, testing laboratories and, potentially, a slag-processing yard is more efficient than two industries working apart.
7.4 Scrap: a supply chain to build
Scrap is the cheapest iron unit for an arc furnace and the one in shortest supply in Central Africa. Cameroon’s existing steel mills already import about 60% of their metallic needs as billets, and local scrap was reported in September 2026 to cover only about 40% of the sector’s needs [S98]. The only national estimate of scrap arising, 53,000 to 62,000 t a year in 2006, is small against these needs [S168]. Recorded exports of ferrous scrap from Cameroon have fallen to almost nothing since 2019, which suggests that most collected scrap is now used at home [S94].
A Kribi cluster can enlarge the scrap supply in two ways. Locally, the port, the industrial zone, the construction sites of a fast-growing coastal region and the end-of-life vehicles and equipment of the South Region generate scrap that is not collected systematically today. A licensed scrap-processing yard in the zone, with shears, balers and radiation and contamination screening, would raise its quality and value. Regionally, coastal shipping can bring scrap from neighbouring ports to Kribi’s deep-water quay in bulk. Both create jobs in collection, sorting and transport, much of it in small enterprises.
7.5 Industrial gases, electrodes, refractories and maintenance
An arc furnace uses oxygen to accelerate melting and refine the steel, typically about 25 to 45 Nm³ per tonne of liquid steel [S112]. At 1 Mtpa, one works would need about 37 million Nm³ a year [S112]. At this scale gas companies normally build an air-separation unit beside the anchor customer, under a long-term supply contract, and sell surplus nitrogen, argon and oxygen to other users: fabricators, hospitals, food processors and laboratories. An anchor steel tenant is therefore how a zone acquires an industrial-gas supply.
Graphite electrodes are consumed at about 2 to 6 kg per tonne of steel in European arc furnaces [S76], refractories line every furnace and ladle, and rolling mills consume rolls, guides and lubricants. These are imported products, but their storage, handling, refurbishment and the skilled maintenance around them are local services. A cluster of two or three melt shops and several mills would sustain on-site workshops for machining, roll grinding, electrical repair and refractory installation, and a testing laboratory accredited to Cameroonian and international product standards.
7.6 Downstream fabrication: what the region still imports
The clearest test of downstream potential is what the region imports in finished form. UN Comtrade data for Cameroon show substantial imports in 2023 of steel products that are made from bars, rods and sections, or that a coastal steel cluster could make (Table 7.1).
Table 7.1 sourcedSelected Cameroonian imports of steel products and the cluster activities that could supply them, 2023
| Product (HS code) | Imports, 2023 | Cluster activity that could supply it | Link to a melt shop and mills | Source |
|---|---|---|---|---|
| Structures and parts of structures (7308) | 25.7 kt; US$58.0 million | Structural fabrication: frames, towers, bridges, warehouses | Uses sections, angles and plate | [S94] |
| Sections, angles and shapes (7216) | US$26.3 million | Sections mill | Direct product of a sections line | [S94] |
| Welded tubes and pipes (7306) | 9.5 kt; US$26.0 million | Tube welding from strip | Needs strip; later-phase option | [S94] |
| Wire of iron or steel (7217) | 3.6 kt; US$5.1 million | Wire drawing, nails, mesh, fencing | Uses wire rod | [S94] |
| Cold-rolled flat products (7209) | 47.5 kt; US$52.0 million | Not a long-products activity | Indicates future flat-steel demand | [S94] |
| Billets and other semi-finished steel (7207) | 161.4 kt; US$151.7 million | Merchant billets from a melt shop | Direct product of a melt shop; the largest single steel import | [S94] |
Source: UN Comtrade public API, Cameroon as reporter, 2023 (latest year reported) [S94]. Values as declared; tonnages where reported.
The largest line is billets, which the existing re-rollers import for about 60% of their charge [S98]: a melt shop at Kribi can sell merchant billets to them as well as rolling its own wire rod and rebar, which is how its tonnage displaces imports rather than adding to a rebar market that is already saturated (White paper 04, Chapter 9). Beyond billets, two activities stand out. Rebar processing (cut-and-bend services, welded mesh, prefabricated cages) moves value from construction sites into factories, improves quality and reduces waste; it is a natural neighbour of a rebar and wire-rod mill. Structural fabrication of steel frames, warehouses, transmission towers and bridges uses sections and plate, and Cameroon imported about US$58 million of fabricated structures in 2023 [S94]. Both are labour-intensive and suited to Cameroonian small and medium enterprises if they can buy steel locally and on credit.
7.7 Jobs and skills
Steel’s employment case rests on its linkages more than on its direct jobs. A global study for the world steel association estimated that every two jobs in the steel industry support about thirteen in its supply chain [S107]. Such multipliers are upper bounds for Cameroon, where supply chains are thinner, but they show where the jobs are: in transport, maintenance, scrap collection, construction and services. For one tenant, Cameroon Steel’s indicative planning figures show about 500 direct jobs (450 to 550) and about 1,000 indirect jobs (800 to 1,500) in a first phase, and about 1,100 direct jobs (900 to 1,300) at full capacity [S112]. KPIZ’s target of up to 150,000 direct and indirect jobs across the whole zone over fifteen years assumes many such anchors [S03].
The constraint is skills. Cameroon has engineering schools and technical institutes, but few if any dedicated programmes in ferrous metallurgy; the national polytechnic school in Yaoundé, for example, lists no metallurgy department [S156]. A cluster creates the scale at which a shared training centre with the region’s universities and equipment suppliers becomes viable. The 2025 investment ordinance requires investors to present a programme of local skills development, technology transfer and local hiring [S23]; a cluster can meet that requirement more effectively together than tenant by tenant.
Table 7.2 derivedCluster services for a Kribi steel platform: who provides them and what the zone should do
| Service | Demand created by one 1 Mtpa works | Typical provider | Zone action |
|---|---|---|---|
| Oxygen, nitrogen, argon | About 37 million Nm³ a year of oxygen [S112] | Gas company with an on-site air-separation unit | Reserve a plot beside the steel cluster; allow pipeline corridors |
| Slag processing | About 149 kt a year of slag [S112] | Specialist processor or joint venture with a cement plant | Designate a slag yard; adopt an aggregate standard for zone roads |
| Scrap processing | Several hundred thousand tonnes a year of scrap at full capacity [S112] | Licensed scrap merchants | Licensed scrap yard with screening; coastal-shipping berth access |
| Hazardous-waste management | About 16 kt a year of furnace dust [S112] | Licensed operator | Shared secure cell or export route (Chapter 5) |
| Maintenance and workshops | Continuous; shutdown peaks | Local and international contractors | Light-industry plots near the steel cluster |
| Testing and certification | Every heat and every product batch | Accredited laboratory | Shared laboratory with cement and construction-materials tenants |
| Training | Hundreds of operators and technicians per phase | Universities, institutes, equipment vendors | Shared training centre in the zone |
Source: quantities from Cameroon Steel indicative planning figures [S112]; zone actions are Cameroon Steel recommendations.
7.8 Designing for exchange
Clusters do not arise from proximity alone. The zone can make them more likely by four choices made early:
- Adjacency in the master plan. Put the steel cluster next to the bulk berth and the high-voltage substation, the slag yard and gas plant next to the steel cluster, cement within conveyor distance of the slag yard, and fabrication near the zone gate and the road to Douala.
- Corridors for pipes and conveyors. Reserve rights of way between plots for oxygen pipelines, slag conveyors and power cables before plots are allocated.
- A by-product exchange register. Publish, with tenants’ consent, the by-products each produces and the inputs each needs, as zones in Asia and Europe do, so that exchanges are found early.
- Shared services under one contract. Let KPIZ tender laboratories, training, fire response and hazardous-waste management once for the whole zone rather than tenant by tenant.
Other sources cited in the English text
- S20Zone industrielle Kribi: 400 milliards FCFA investis et 53 entreprises autorisées à s’implanter depuis 2018. Investir au Cameroun, 20 May 2025.investiraucameroun.com/gestion-publique/2005-22033-zone-industrielle-k…
- S03Zone industrialo-portuaire de Kribi (KPIZ): jusqu’à +8 points de croissance et 150 000 emplois attendus sur 15 ans. Investir au Cameroun, 4 March 2026.investiraucameroun.com/gestion-publique/0403-23163-zone-industrialo-po…
- S36Cameroon speeds up Kribi bitumen plant with tax breaks and refining licence. Business in Cameroon, 10 June 2026.businessincameroon.com/public-management/1006-16302-cameroon-speeds-up…
- S19Port de Kribi: un protocole d’accord signé pour un terminal agro-industriel de 50 milliards de FCFA. Investir au Cameroun, 9 October 2026.investiraucameroun.com/gestion-publique/0910-23942-port-de-kribi-un-pr…
- S75Environmental, Health, and Safety Guidelines for Integrated Steel Mills. IFC, World Bank Group, 30 April 2007.ifc.org/content/dam/ifc/doc/2000/2007-integrated-steel-mills-ehs-guide…
- S155Slag recycling: valuable by-products (Euroslag 2018 statistics for steelworks slag). ReCOVERY magazine, February 2020.recovery-worldwide.com/en/artikel/slag-recycling-3528047.html
- S76Best Available Techniques Reference Document for Iron and Steel Production (EUR 25521). European Commission, Joint Research Centre, 2013.bureau-industrial-transformation.jrc.ec.europa.eu/sites/default/files/…
- S27Bilan et perspectives: les voyants sont au vert. Port Autonome de Kribi, 13 March 2025.Cited by title and date
- S18Cameroun: le port de Kribi engage 3,5 milliards FCFA pour préparer l’arrivée de nouveaux industriels. EcoMatin, 11 May 2026.ecomatin.net/cameroun-le-port-de-kribi-engage-35-milliards-fcfa-pour-p…
- S105Dangote exported 1Mt of clinker from Nigeria to Cameroon and Ghana in 2025. Global Cement, 27 March 2026.globalcement.com/news/20591-dangote-exported-1mt-of-clinker-from-niger…
- S168La récupération et le recyclage des déchets ferromagnétiques: analyse de la situation au Cameroun (Déchets, Revue francophone d’écologie industrielle n°48). Bidoung J., Fomethe A., Yantio G., Melo U. (ENSP Yaoundé / MIPROMALO), 2007.eid.episciences.org/7942/pdf
- S156École nationale supérieure polytechnique de Yaoundé: departments (homepage). ENSP Yaoundé, University of Yaoundé I.polytechnique.cm/
- S23Ordonnance n° 2025/002 du 18 juillet 2025 fixant les incitations à l’investissement en République du Cameroun. Presidency of the Republic (copy published by GECAM), 18 July 2025.legecam.cm/wp-content/uploads/2025/08/ordonnance_n_2025_002_du_18_07_2…
本章引用的资料来源
方括号内的标记对应以下来源(按原文语言列出),完整列表见附录。 完整来源列表
- S112Cameroon Steel reference configuration RC-1 (planning estimate), edition 10 October 2026. Cameroon Steel,2026年10月10日.按标题和日期引用
- S107Economic and social impact of the global steel industry. worldsteel / Oxford Economics,2019年5月.worldsteel.org/wp-content/uploads/Steel-social-and-economic-impact.pdf
- S35La ZIPK rayonne avec l’inauguration de la cimenterie CIMPOR. Port Autonome de Kribi,2024年7月19日.按标题和日期引用
- S37Cameroon: Atlantic Group amends investment agreement for 1-million-tonne Kribi cement plant. Ecofin Agency,2026年2月27日.ecofinagency.com/news-industry/2702-53339-cameroon-atlantic-group-amen…
- S93Évolution du commerce extérieur en 2025 (version provisoire). Institut National de la Statistique (INS), Cameroon,2026年2月.ins-cameroun.cm/wp-content/uploads/2026/04/Note-sur-le-commerce-exteri…
- S98Cameroun: le groupe Prometal décroche 26 milliards FCFA auprès d’Afreximbank pour renforcer sa production d’acier. Sikafinance,2026年9月30日.sikafinance.com/marches/cameroun-le-groupe-prometal-decroche-26-millia…
- S94UN Comtrade public API: Cameroon and CEMAC members, HS 72 and 73 imports, 2019 to 2024. United Nations Statistics Division.comtradeapi.un.org/public/v1/preview/C/A/HS
引用本章
Cameroon Steel(2026)。基础设施若能同步跟进,克里比可成为中部非洲的钢铁平台(中文摘要版)。白皮书02,第7章:钢铁龙头企业使克里比工业区成为自我供给的产业集群。CS-WP-02。https://www.cameroon-steel.com/zh/library/kribi-steel-platform/cluster-effects/
来源