白皮书05 · 第7章 · 中文摘要
100万吨/年直接还原厂每年约需90亿立方英尺天然气:成本可承受,但须有认证气源和直接还原级矿石
气基直接还原每吨直接还原铁消耗9.2至10吉焦天然气,因此100万吨/年模块每年约需84至91亿立方英尺,相当于喀麦隆2025年产量的11%至12%,接近克里比电厂用气量的两倍。按2025年国内气价,每吨直接还原铁的燃气成本为27至51美元,仅占2026年3月热压块铁运抵意大利价格(每吨340至370美元)的一小部分。在克里比炼铁的障碍不是气价,而是二十年的认证供气和直接还原级球团来源。
本页为本章中文摘要;英文全文附于其后,可展开阅读。
关键数据。2025年全球直接还原铁产量1.51亿吨,其中65.1%为气基;按Midrex工厂统计,撒哈拉以南非洲仅9万吨 [S94];世界钢铁协会的数据包含该统计之外工厂的估算,东非(乌干达、肯尼亚、坦桑尼亚)直接还原铁产量约270万吨 [S95]。100万吨/年模块每天约用气2300至2500万立方英尺,二十年合计约1700至1800亿立方英尺,占萨纳加南可能剩余储量的很大部分(推算)。按电力行业气价(约3.2美元/千立方英尺),每吨直接还原铁燃气成本约27至29美元;按工业气价(约5.0至5.6美元)约42至51美元;按2025年液化原料气最高价(8.97美元)约75至82美元(图7.2)。相比之下,2026年9月巴西生铁离岸价约445美元/吨 [S99]。直接还原需要铁品位至少64%的矿石,这类矿石不足全球供应的20% [S101];姆巴拉姆(Mbalam)直运矿品位在62%以上,适合高炉,需经选矿和造球才能用于直接还原。2023年《矿业法》规定15%的矿产须在本地加工 [S27],本地加工政策意味着需要为直接还原配置天然气。RC-1一期至三期采用进口直接还原铁或热压块铁(约占金属炉料30%);一期废钢中仅约3万吨/年(0至6万吨)来自国内,其余进口,一期经港口进口的金属料和辅料约35.1万吨/年 [S07]。2034年后的100万吨/年模块仅作为储备方案;直接还原级球团的散货装卸取决于2025年11月4日签署谅解备忘录、预计五至六年内建成的矿石码头 [S80][S81];25万吨/年的小型模块每年仅需约21至23亿立方英尺,可作为过渡。
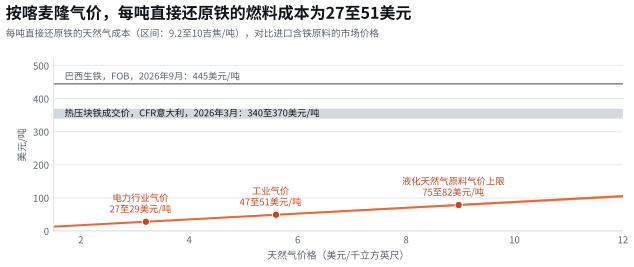
资料来源:SNH 2025年气价 [S05];直接还原用气 [S39][S41];SteelOrbis,2026年3月16日,热压块铁CFR意大利 [S18];GMK Center,2026年10月4日,巴西生铁FOB [S99]。
英文全文 12分钟 · 2688词A 1 Mtpa direct-reduction plant would need about 9 bcf of gas a year: affordable, but only with certified supply and DR-grade ore
Gas-based direct reduction consumes 9.2 to 10 GJ per tonne of DRI, so a 1 Mtpa module would need about 8.4 to 9.1 bcf of gas a year, 11% to 12% of Cameroon’s 2025 output and nearly twice what the Kribi power plant burned. At 2025 domestic prices, the gas would cost US$27 to US$51 per tonne of DRI, a small share of the US$340 to US$370 a tonne at which hot-briquetted iron traded into Italy in March 2026. The obstacles to making iron at Kribi are not the price of gas but twenty years of certified supply and a source of direct-reduction-grade pellets.
7.1 Direct reduction turns gas into the chemistry of ironmaking
Iron ore is iron oxide. To make steel from ore, the oxygen must be removed, and in direct reduction this is done in the solid state, well below the melting point of iron. Pellets of high-grade ore descend through a shaft furnace while a hot reducing gas, rich in hydrogen and carbon monoxide, flows upwards. The gas is made from natural gas, either in a separate reformer (as in the MIDREX process) or inside the shaft itself (as in the Energiron ZR process). The product is direct-reduced iron (DRI), a porous metallic iron that is either charged hot into a neighbouring arc furnace, cooled, or pressed into dense briquettes, hot-briquetted iron (HBI), that can be shipped safely.
Natural gas therefore plays two roles: it provides the heat and it provides the reducing agents. The published benchmarks are close to one another:
- MIDREX plants use about 2.35 Gcal of natural gas per tonne of DRI, about 9.84 GJ [S93];
- the Energiron process uses about 10 GJ of natural gas and about 73 kWh of electricity per tonne of DRI, and about 8.3 GJ and 60 kWh when 73% of the reducing gas is hydrogen [S39];
- Suez Steel’s Energiron ZR plant in Egypt reported sustained consumption below 2.2 Gcal per tonne, about 9.2 GJ, in April 2026 [S41].
The technology is mature and widely used. World DRI production reached 151.0 Mt in 2025, of which 65.1% was gas-based; MIDREX plants made 54.5% and HYL/Energiron plants 10.0% of the total [S94]. HBI accounted for 11.6 Mt, or 7.7% of DRI, and international trade in DRI and HBI was about 10.8 Mt [S94]. Africa’s gas-based DRI is concentrated in North Africa, with Algeria at 6.7 Mt, Egypt at 6.1 Mt and Libya at 1.75 Mt. On Midrex plant statistics, sub-Saharan Africa produced only 0.09 Mt in 2025, and its two gas-based plants were idle [S94]; worldsteel, whose figures include estimates for plants outside that survey, puts East African DRI output at about 2.7 Mt in 2025, in Uganda, Kenya and Tanzania [S95].
Source: Midrex, 2025 World Direct Reduction Statistics [S94]; worldsteel, World Steel in Figures 2026 [S95]; EC ICIT Energiron [S39]; Danieli, Suez Steel (2026) [S41]; Midrex history [S96].
7.2 Gas demand rises in proportion to module size
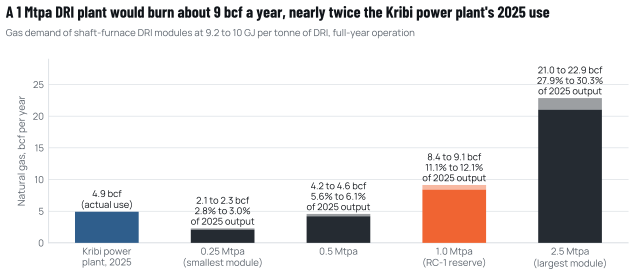
Shaft-furnace modules are built in a wide range of sizes. The smallest recent example is a 0.25 Mtpa Energiron ZR micro-module that started in Bolivia in October 2025 [S94]; the first 1.0 Mtpa MIDREX MEGAMOD was built for JSW at Dolvi in India [S96]; and the largest single module, 2.5 Mtpa, has operated in Algeria since 2018 [S96][S94]. Figure 7.1 converts these sizes into annual gas demand.
Source: DRI gas use [S39][S41]; module sizes [S94][S96]; SNH 2025 output and Kribi power plant use [S05]; 1 Mscf = 1.094 GJ (derived).
A 1 Mtpa module, the size that RC-1 reserves for a later phase based on Cameroonian ore, would need about 8.4 to 9.1 bcf a year, or about 23 to 25 MMscf a day (derived). That is 11% to 12% of 2025 output and about 1.7 to 1.9 times the gas burned by the Kribi power plant in 2025. Over a twenty-year life, it would consume about 170 to 180 bcf (derived), a large share of what may remain in Sanaga Sud (Chapter 6).
The electricity demand of a DRI plant is modest by comparison: at about 73 kWh per tonne [S39], a 1 Mtpa module would use about 73 GWh a year (derived), about a tenth of the electricity of a 1 Mtpa melt shop and rolling mill. The larger electrical effect is in the arc furnace, where each additional 10% of DRI in the charge adds about 14.5 kWh per tonne of liquid steel [S39].
RC-1 treats the DRI module as a reserve: about 1 Mtpa of DRI capacity (0.8 to 1.1 Mtpa), planned for after 2034, subject to ore quality of at least 64% Fe, gas supply and approvals [S07]. Until then, the plant’s ore-based iron units would be imported DRI or HBI, about 30% of the metallic charge in the planning case [S07].
7.3 Ore-based iron units matter because Cameroon is short of scrap
The reason an electric steelworks in Cameroon needs DRI at all is the scarcity of scrap. Local scrap covers only about 40% of the needs of Cameroon’s existing mills [S32], and billets, the semi-finished steel those mills roll, were the largest steel import in 2023, at 161 kt [S11]. In September 2026, Prometal arranged a €40m facility with Afreximbank to import billets as Cameroonian scrap became scarcer [S32][S97]. A new melt shop cannot assume that domestic scrap will cover its needs.
RC-1 therefore plans a mixed charge. At nameplate, the Phase 1 furnace would melt about 363,000 t of metallics a year, of which about 254,000 t of scrap and about 109,000 t of imported DRI or HBI [S07]. Only about 30,000 t a year of the scrap (a planning range of 0 to 60,000 t) is expected from domestic sources, against the only quantified national study, which put scrap arising at 53,000 to 61,833 t a year in 2006 [S98]; the rest would be imported, so that Phase 1 would bring about 351,000 t a year of metallics and consumables through the port [S07] (White paper 02). DRI and HBI also bring a metallurgical benefit: they contain almost none of the copper and tin that accumulate in recycled scrap, so they dilute these residual elements, which matters for wire rod and other demanding products. The energy cost of that benefit is the additional furnace electricity described in Chapter 1. The gas question in this chapter is therefore the question of where, in the long run, the plant’s clean iron units come from: from abroad, as DRI or HBI made with other countries’ gas, or from Kribi, made with Cameroon’s.
7.4 At Cameroonian prices, the gas would cost US$27 to US$51 per tonne of DRI
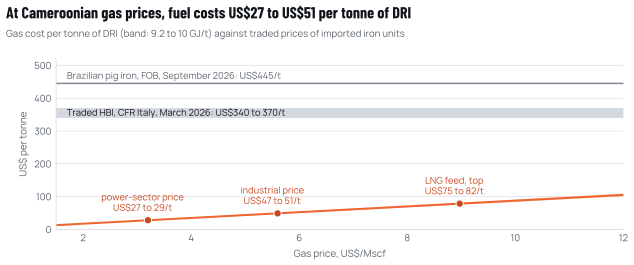
Figure 7.2 shows the gas cost per tonne of DRI as a function of the gas price, against two traded benchmarks for imported iron units.
Source: SNH 2025 gas prices [S05]; DRI gas use [S39][S41]; SteelOrbis, 16 March 2026, HBI CFR Italy [S18]; GMK Center, 4 October 2026, Brazilian pig iron FOB [S99].
At the power-sector price of about US$3.2/Mscf, the gas for a tonne of DRI would cost about US$27 to US$29; at the industrial price of about US$5.0 to 5.6/Mscf, about US$42 to US$51; and at the top of the 2025 LNG feed price, US$8.97/Mscf, about US$75 to US$82 (derived). For comparison, Libyan HBI was offered at about US$370 a tonne CFR Italy in March 2026 and Venezuelan HBI at about US$340 [S18]; Brazilian pig iron fell to about US$445 a tonne FOB in September 2026 [S99]; and Chinese billets were offered at US$465 to US$470 FOB on 3 October 2026 [S09].
The comparison shows that gas is not the dominant cost of DRI at Cameroonian prices. The largest cost is the iron-bearing feed: DR-grade pellets, whose price is set on international markets and carries a premium over ordinary iron ore. The benchmark for ordinary 62% Fe ore averaged US$100.2 per dry tonne in 2025 [S100]; DR-grade pellet prices were not available in a form that could be verified for this paper. A domestic DRI plant would therefore be competitive with imported HBI only if it combines cheap gas with a reliable source of pellets, ideally from Cameroonian ore.
7.5 Ore quality decides whether Cameroonian ore can feed a DRI plant
Shaft furnaces need high-grade feed. worldsteel notes that current DRI processes require ore with at least 64% iron, a quality that represents less than 20% of global supply [S101]. Public reporting of Cameroon’s Mbalam deposit refers to direct-shipping ore grading above 62% Fe [S08], which is suited to blast furnaces and sinter plants rather than to direct reduction. Producing DR-grade feed from Cameroonian ore would therefore require concentration and pelletising, a substantial investment of its own.
The policy framework points in this direction. Cameroon’s Mining Code of 2023 provides for local transformation of 15% of mine production [S27]. Cameroon Steel’s sister company, Cameroon Mining Company, holds the Mbalam exploitation permit [S08]; its mining convention is reported to commit it to transform 15% of its production locally, and the same press report presents Cameroon Steel as the future national steel hub of that programme [S102]. Making iron at Kribi from Cameroonian ore would satisfy that intent more fully than any other route. It is also why the gas question matters: a local-transformation policy for iron ore implies a gas allocation policy for direct reduction.
Agora Industry’s analysis of the global steel transition warns that DR-grade ore supply is likely to lag demand by 2030 [S103]. That cuts both ways: it raises the value of a future Cameroonian DR-pellet supply, and it means that a plant at Kribi cannot assume imported DR pellets will remain cheap or abundant.
7.6 Make or buy: domestic DRI against imported DRI and HBI
Table 7.1 compares the two ways an electric steelworks at Kribi could obtain ore-based iron units.
Table 7.1 Imported DRI and HBI against a domestic gas-based DRI module at Kribi
| Criterion | Imported DRI or HBI (RC-1 Phases 1 to 3) | Domestic gas-based DRI at Kribi (RC-1 reserve, after 2034) |
|---|---|---|
| Gas needed | None | About 8.4 to 9.1 bcf a year for 1 Mtpa |
| Electricity | EAF penalty only (about 14.5 kWh/t per 10% DRI) | About 73 GWh a year for the module, plus EAF penalty |
| Iron feed | Bought as finished DRI or HBI | DR-grade pellets (at least 64% Fe), imported or from Cameroonian concentrate |
| Market exposure | International DRI and HBI trade of about 10.8 Mt (2025); few exporters | Pellet market; gas price formula |
| Logistics | Import through existing port terminals | Pellet import or domestic supply; bulk handling depends on the mineral terminal agreed in a memorandum of understanding in November 2025, with completion expected within five to six years |
| Capital | None for ironmaking | A shaft furnace, gas supply and pellet handling |
| Carbon | Upstream emissions of the exporter (RC-1 assumes about 0.7 t CO₂ per t DRI) | Direct emissions of gas reduction at Kribi; electricity from a low-carbon grid; hydrogen blending possible later |
| Value added in Cameroon | Melting and rolling only | Ironmaking, and eventually ore processing |
| Main precondition | Reliable import supply and price | Certified gas reserves, a price formula, a pipeline and pellet supply |
Source: [S39][S41][S94][S101][S80][S81][S07]; Cameroon Steel analysis.
The table explains RC-1’s sequence. Imported DRI or HBI requires no gas and no capital for ironmaking, and it allows the melt shop and mills to be built and run while the gas and ore questions are resolved. A domestic module adds value and resilience but depends on three conditions that do not yet exist: certified gas for its life, a published price formula, and a pellet supply. The international market for DRI and HBI is also thin: trade data show about 10.8 Mt in 2025, or about 13.2 Mt including origins under sanctions, with Russia (as HBI) and India the largest exporters [S94]. That is a supply-security argument for eventually making iron at home.
7.7 A small module could be a stepping stone
There is a middle path. A 0.25 Mtpa module of the size started in Bolivia in 2025 [S94] would need only about 2.1 to 2.3 bcf a year, less than half of what the Kribi power plant used in 2025 and under 3% of 2025 national output (derived). It would cover about two-thirds of RC-1’s planned full-build-out DRI use of about 0.36 Mt a year [S07], could run on imported pellets while Cameroonian concentrate is developed, and would give the gas sector a first long-term industrial customer of manageable size. Whether such a module is economic at that scale is a question for a feasibility study; this paper only notes that the gas required is within reach.
7.8 Hydrogen later, gas first
Shaft furnaces can use hydrogen in place of part of the natural gas. The Energiron data show that with 73% hydrogen in the reducing gas, natural gas use falls from about 10 to 8.3 GJ per tonne [S39]. Fully hydrogen-based reduction needs about 54 kg of hydrogen per tonne of DRI, which, at current electrolyser efficiencies, implies roughly 2.4 to 2.8 MWh of electricity per tonne of DRI for the hydrogen alone (derived from [S93][S35]). For a 1 Mtpa module, that would be 2.4 to 2.8 TWh a year, about a third of Cameroon’s entire 2025 generation (derived). Hydrogen-based iron at Kribi is therefore a long-term option tied to new hydro capacity, not a near-term plan (Chapter 8). A gas-based plant designed to accept hydrogen blending keeps the option open.
7.9 What would make a DRI plant at Kribi possible
The conditions follow directly from this chapter and the previous one:
- An independent reserve audit showing at least twenty years of supply at about 9 bcf a year for a 1 Mtpa module, or a smaller module sized to what is certified.
- A gas allocation and price formula for industrial chemical use, separate from power-sector gas, with clear tax treatment.
- A pipeline from the gas receiving facilities at the Kribi power plant to the industrial zone.
- A pellet strategy: imported DR pellets first, with a path to Cameroonian concentrate that matches the local-transformation policy.
- Bulk port capacity for pellets. The mineral terminal agreed in a memorandum of understanding on 4 November 2025 is expected by PAK’s Director General to be completed within five to six years [S80][S81], which would precede a module planned for after 2034; neither date is firm, so a DRI plan should not assume the terminal until its first stage is financed (White paper 02, Chapter 2).
None of these is needed for Phase 1 of an electric steelworks. All of them are needed before a DRI module can be financed, which is why they belong in national energy and mining policy now rather than in a project’s later phases.
Other sources cited in the English text
- S93Hydrogen uses in ironmaking (V. Chevrier, Midrex). US DOE H2@Scale, 1 Aug 2018.energy.gov/sites/prod/files/2018/08/f54/fcto-h2-scale-kickoff-2018-8-c…
- S96Midrex history. Midrex Technologies, n.d., accessed Oct 2026.midrex.com/history/
- S32Cameroun: le groupe Prometal décroche 26 milliards FCFA auprès d’Afreximbank…. Sikafinance, 30 Sep 2026.sikafinance.com/marches/cameroun-le-groupe-prometal-decroche-26-millia…
- S11UN Comtrade public API, Cameroon (reporter 120), HS 72/73 and 6-digit lines, 2019-2023. UN Statistics Division.comtradeapi.un.org/public/v1/preview/C/A/HS?reporterCode=120&period=20…
- S9740 millions d’euros d’Afreximbank: Prometal sécurise ses billettes d’acier alors que la ferraille camerounaise s’épuise. Cameroun24, 10 Oct 2026.cameroun24.net/article/76267-40-millions-d-euros-d-afreximbank-prometa…
- S98Bidoung J., Fomethe A., Yantio G., Melo U., La récupération et le recyclage des déchets ferromagnétiques: analyse de la situation au Cameroun (Déchets, Revue francophone d’écologie industrielle n°48). ENSP Yaoundé / MIPROMALO, Q4 2007.eid.episciences.org/7942/pdf
- S09Weekly steel prices (archive 40468). Arab Iron & Steel Union (AISU), 3 Oct 2026.aisusteel.org/en/archives/40468
- S100Commodity Markets Outlook, Historical Data, Annual (xlsx). World Bank, 2 Sep 2026.thedocs.worldbank.org/en/doc/74e8be41ceb20fa0da750cda2f6b9e4e-00500120…
- S08Kribi: le Premier ministre, chef du gouvernement est là. Cameroon Tribune, 30 Dec 2024.cameroon-tribune.cm/article.html/68499/fr.html/details_2
- S102Cameroon Mining Company confirme l’entrée du projet Mbalam dans sa phase irréversible d’exécution. Camer.be via AllAfrica, 12 Dec 2025.fr.allafrica.com/stories/202512120475.html
- S10315 Insights on the Global Steel Transformation. Agora Industry, 15 Jun 2023.agora-industry.org/publications/15-insights-on-the-global-steel-transf…
- S35Iron and Steel Technology Roadmap. IEA, Oct 2020.iea.blob.core.windows.net/assets/eb0c8ec1-3665-4959-97d0-187ceca189a8/…
本章引用的资料来源
方括号内的标记对应以下来源(按原文语言列出),完整列表见附录。 完整来源列表
- S942025 World Direct Reduction Statistics. Midrex Technologies,2026年9月.midrex.com/world-dri-statistics/world-dri-production-reaches-151-0-mt-…
- S95World Steel in Figures 2026. World Steel Association (worldsteel),2026年6月4日.worldsteel.org/data/world-steel-in-figures/world-steel-in-figures-2026…
- S99Average prices for Brazilian pig iron fell by $20/t in September. GMK Center,2026年10月4日.gmk.center/?p=129748
- S101Climate change and the production of iron and steel (policy paper). worldsteel,网页访问于2026年10月10日.worldsteel.org/climate-action/climate-change-and-the-production-of-iro…
- S27Loi n° 2023/014 du 19 décembre 2023 portant Code minier (official text, mirror). Rural-info (copy of the official text),2023年12月19日.rural-info.net/wp-content/uploads/2024/11/Loi-N°2023-014-du-19-decembr…
- S07Cameroon Steel reference configuration RC-1 (planning estimate), edition 10 October 2026 (RC-1.1): phases, benchmarks with ranges, indicative balances and schedule. Cameroon Steel,2026年10月10日.按标题和日期引用
- S80Port de Kribi: un terminal minéralier d’avenir (memorandum of understanding for a mineral terminal). Port Autonome de Kribi,2025年11月4日.按标题和日期引用
- S81Zone industrialo-portuaire de Kribi (KPIZ): jusqu’à +8 points de croissance et 150 000 emplois attendus sur 15 ans. Investir au Cameroun,2026年3月4日.investiraucameroun.com/gestion-publique/0403-23163-zone-industrialo-po…
- S05Données pétrolières 2025. SNH,发布:2026年6月.snh.cm/wp-content/uploads/2026/06/Donnees-petrolieres-2025.pdf
- S39ENERGIRON technology (DRI-EAF with natural gas or H₂). EC ICIT,引用:2026年2月12日.innovation-centre-for-industrial-transformation.ec.europa.eu/innovativ…
- S41Suez Steel sets new benchmark in energy consumption for DRI production. Danieli,2026年4月16日.danieli.com/en/news-media/news/suez-steel-sets-new-benchmark-energy-co…
- S18European buyers uninterested in BPI and HBI purchases, prices up nominally due to freight. SteelOrbis,2026年3月16日.steelorbis.com/steel-prices/steel-prices-market-analyses/scrap-and-raw…
引用本章
Cameroon Steel(2026)。喀麦隆水电主导的电网可为低碳钢铁供电,前提是大用户获得稳定供电、明确电价和天然气(中文摘要版)。白皮书05,第7章:100万吨/年直接还原厂每年约需90亿立方英尺天然气:成本可承受,但须有认证气源和直接还原级矿石。CS-WP-05。https://www.cameroon-steel.com/zh/library/energy-for-industry/gas-for-direct-reduction/
来源