白皮书05 · 第10章 · 中文摘要
五项规则而非补贴,可使喀麦隆能源体系为重工业做好准备
喀麦隆无需补贴能源来吸引电炉钢厂,而需要公布大用户据以规划和融资的规则。五项措施可使能源体系对重工业具备可融资性:10兆瓦以上大用户电价框架;波动负荷电网规范;FLNG撤离后的国内天然气配置与价格框架;可执行的过网输电和第三方准入;围绕工业区对变电站、稳定容量和水电进行一体化规划。每项措施惠及所有大用户,且都不需要为单一项目投入公共资金。
本页为本章中文摘要;英文全文附于其后,可展开阅读。
本章目录(1)
关键数据与时序。第一,到2027年由ARSEL和SONATREL出台大用户电价框架(两部制、激励避开系统高峰的用电安排、无功规则、按公式调价、期限10至20年,存量高压合同在公开期限内逐步并轨)和波动负荷电网规范(采用IEC TR 61000-3-7方法,公布90千伏和225千伏节点短路容量)。第二,2027年起由SNH及主管部门开展萨纳加南和埃博梅(Ebome)气田独立储量审计,2027至2028年出台按用户类别的配置与价格公式,明确石油产品特别税的适用。第三,到2028年落实第2011/022号法律下的过网输电:公布市场规范和平衡规则、备用电价及来源证书。第四,由PAK、克里比港工业区股份有限公司(KPIZ S.A.)、SONATREL、电力公司、SNH和MINEE持续推进克里比园区一体化规划:需求登记、按里程碑预留容量、浅接入费用、克里比稳定容量以及新建水电的工业承购。第五,每年公布短路容量、天然气平衡和电网排放因子等能源数据。图10.1将上述措施与已排定的公开里程碑和RC-1目标并列:电网和港口里程碑在2026年底至2027年初,政策措施可在2028年前到位,一期计划2029年第一季度开工、2030年下半年首炉出钢、2031年爬坡,而欧盟对本土钢厂的免费配额将于2034年归零 [S109]。作为回报,大用户可提供长期高负荷率需求、自建补偿、可调度负荷、水电锚定承购和数据透明。
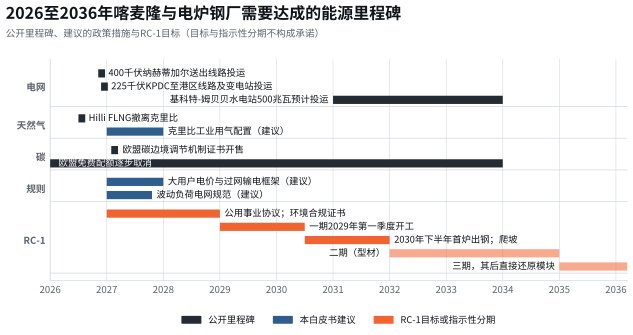
资料来源:Business in Cameroon,2026年10月9日 [S02];PAK,2025年8月6日 [S14];基科特-姆贝贝 [S68];FLNG撤离 [S16];碳边境调节机制 [S108][S109];Cameroon Steel参考配置RC-1(规划估算)指示性进度 [S07]。
英文全文 10分钟 · 2260词Five rules, not subsidies, would make Cameroon’s energy system ready for heavy industry
Cameroon does not need to subsidise energy to attract an electric steelworks; it needs to publish the rules on which large users can plan and borrow. Five steps would make the energy system bankable for heavy industry: a large-user tariff framework above 10 MW; a grid code for fluctuating loads; a domestic gas allocation and price framework after the FLNG; enforceable wheeling and third-party access; and integrated planning of substations, firm capacity and hydro around industrial zones. Each would benefit every large user, and none commits public money to a single project.
10.1 The case for rules rather than deals
The previous chapters show a consistent pattern. Cameroon has the physical ingredients of a low-carbon heavy-industry platform: a hydro grid at about 226 g CO₂e/kWh [S10], a new 225 kV supply to the Kribi industrial-port zone [S14], a gas field next to the port that has just lost its export buyer [S05][S16], and about 115 TWh a year of undeveloped hydro potential [S66]. What it lacks are published rules for the transactions that turn these ingredients into investable supply.
Today, a large user negotiates its electricity price without a published tariff [S01], its connection without a published code for fluctuating loads, its gas without published allocation rules, and its access to independent producers without published wheeling and balancing rules. Each negotiation is bespoke, slow and revisable, and lenders discount it accordingly. The steel producers’ 2023 dispute over tariffs [S44][S45] and the regulator’s 2025 revision of certain high-voltage contracts [S01] show the cost of that uncertainty.
The recommendations below are therefore framed as public rules, not as concessions to one project. They draw on the evidence in Chapters 1 to 9 and are summarised in Table 10.1.
10.2 Publish a large-user tariff framework above 10 MW
What. ARSEL, with the Ministry of Water and Energy (MINEE), should publish a tariff framework for customers above 10 MW connected at 90 kV or 225 kV, extending the logic of the existing MV grid [S54][S03] rather than replacing it. Its principles should be:
- Cost of service at high voltage. The price should reflect the cost of serving a high-voltage, high-load-factor customer: energy, transmission, losses and the cost of firmness, without the distribution and low-voltage costs embedded in the 105 FCFA/kWh system average [S04]. Chapter 3’s indicative stack suggests this is roughly half the system average before firmness is priced.
- Two-part structure with utilisation regimes. A capacity charge on a stated 15-minute maximum demand and an energy charge, with regimes that reward high utilisation, as the MV grid already does above 400 hours a month [S03].
- A reward for scheduled load. Time-of-use energy prices, or a capacity charge measured at the system peak, that reward load moved out of the peak, with any emergency load-shedding capped in hours and events a year and compensated beyond the cap.
- Explicit reactive-energy rules that reward local compensation.
- Indexation by formula. Annual adjustments tied to published indices (hydro purchase prices, gas prices, inflation), replacing discretionary revisions.
- Long terms. Contracts of 10 to 20 years, so that lenders can match them to debt.
- A transition path for legacy contracts. The six legacy high-voltage contracts at about 18.4 FCFA/kWh [S01] should converge over a published period to the framework, so that new and existing users compete on equal terms.
Why. It would give every large user a published basis for its business case, give the utility a principled basis for pricing, and give lenders a framework they can analyse.
10.3 Adopt a grid code for fluctuating loads
What. ARSEL and SONATREL should publish, or confirm and complete, the power-quality chapter of the connection code for large fluctuating loads such as arc furnaces, rolling mills and large motors. ARSEL’s website lists a connection code among its regulatory texts, but its content could not be verified for this paper [S71]. The code should:
- adopt the emission-allocation approach of IEC TR 61000-3-7 for flicker, with the planning levels of Pst 0.8 and Plt 0.6 at high voltage as the default [S13], and a recognised standard for harmonics such as IEEE Std 519-2022 [S73];
- oblige the transmission operator to publish minimum and maximum fault levels at 90 kV and 225 kV nodes, so that investors can screen sites;
- require a connection study for any load above a threshold, with the plant paying for its compensation and the network operator providing the connection strength;
- require permanent power-quality monitoring at the point of common coupling, with data shared between plant and operator, and commissioning tests before acceptance.
Why. Clear obligations protect other users from disturbance and protect the steelworks from open-ended demands. Cameroon already has a domestic precedent to learn from in Prometal’s high-voltage arc-furnace connection in Douala [S42][S01].
10.4 Create a domestic gas allocation and price framework
What. SNH, the ministries responsible for hydrocarbons and energy, and the upstream partners should replace the FLNG-era arrangement with a domestic framework that includes:
- an independent audit of remaining reserves in Sanaga Sud and Ebome, published in summary with a deliverability profile [S17][S84];
- a priority order and indicative volumes for power generation (including firm capacity for industry), industrial heat and chemical uses such as direct reduction;
- price formulas by class of user, set high enough to sustain upstream investment and predictable enough for industrial financing, building on the 2025 reference prices of about US$3.2/Mscf for power and US$5.0 to 5.6/Mscf for industry [S05];
- tax clarity on whether, and at what rate, the special petroleum tax of 70 FCFA/m3 applies to industrial gas [S87];
- infrastructure responsibility for a pipeline from the Kribi gas plant’s receiving facilities to the industrial-port zone;
- standard contract terms, and a rule for how new discoveries such as Yoyo-Yolanda [S17] are brought into the domestic system.
Why. Gas is the only domestic source of firm thermal power and the only near-term route to making iron from Cameroonian ore. Without published allocation rules, neither a firm-capacity contract nor a direct-reduction plant can be financed.
10.5 Make wheeling and third-party access work in practice
What. Law No. 2011/022 already allows independent producers to sell to eligible customers at negotiated prices [S52], and SONATREL publishes a transmission tariff [S53]. The missing pieces are operational:
- publication of the market code and the balancing rules: how a large user’s consumption is matched with its producer’s injections, how imbalances are settled and at what price;
- a back-up and top-up tariff for when the contracted producer is unavailable;
- a certificate of origin scheme, so that hydro or solar supplied under contract can be claimed under the market-based Scope 2 method;
- a published list of the eligibility threshold for customers who may contract directly.
Why. Wheeling would let large users contract directly with new hydro and solar projects, improving their bankability and letting industry claim the low-carbon attribute that Chapter 8 shows is worth more than the grid average.
10.6 Plan substations, firm capacity and hydro around industrial zones
What. PAK, KPIZ S.A., SONATREL, the utility, SNH and MINEE should plan the Kribi industrial-port zone’s energy supply as a single programme:
- a demand register of prospective tenants with phased loads, updated yearly, to size the port substation’s later stage of 330 to 400 MW [S14];
- capacity reservation against project milestones and a reservation fee, so that large users can finance their plants and the zone can plan its expansion;
- shallow connection charges, so that each tenant pays for its dedicated assets and contributes to shared assets through regulated tariffs;
- firm capacity at Kribi, through the extension of the Kribi gas plant within its 330 MW licence [S21][S22] or new capacity, once gas is allocated;
- industrial offtake for new hydro, such as Kikot-Mbebe [S68], so that large users help finance the low-carbon capacity they will consume.
Why. It would align the timing of the zone’s energy supply with its tenants’ investments and avoid the situation, visible nationally today, of industrial demand waiting for transmission [S02].
Table 10.1 Policy recommendations, responsibilities and timing
| No. | Recommendation | Lead | Partners | Suggested timing | Benefit for all large users |
|---|---|---|---|---|---|
| 1 | Large-user tariff framework above 10 MW | ARSEL | MINEE, utility, SONATREL, industry bodies | Consultation 2027; in force 2028 | Published, cost-based price and indexation |
| 2 | Grid code for fluctuating loads | ARSEL, SONATREL | Utility, industry | 2027 | Clear power-quality obligations; published fault levels |
| 3 | Domestic gas allocation and price framework | SNH and the ministries responsible for hydrocarbons and energy | Upstream partners, ARSEL | Reserve audit 2027; framework 2027 to 2028 | Financeable gas contracts for power and industry |
| 4 | Wheeling, balancing and certificates of origin | ARSEL, SONATREL | IPPs, utility | 2027 to 2028 | Direct contracts with hydro and solar producers |
| 5 | Integrated energy planning for the Kribi zone | PAK, KPIZ S.A. | SONATREL, utility, SNH, MINEE | Demand register 2027; later-stage substation design 2027 to 2028 | Capacity when tenants need it; fair connection charges |
| 6 | Energy data transparency | ARSEL, SNH, SONATREL | Statistics institute | Annual from 2027 | Fault levels, gas balance, grid emission factors |
Source: Cameroon Steel recommendations, based on the evidence in Chapters 1 to 9. Timing is indicative.
The sixth line in the table is a cross-cutting request. Several of this paper’s evidence gaps (Chapter 11) are basic public data: the fault levels at major nodes, a reconciled national gas balance, and a harmonised grid emission factor. Publishing them annually would cost little and would help every investor.
10.7 Sequencing the five steps
The five steps do not need to wait for one another, but some are needed sooner than others.
First, by 2027: the tariff framework and the grid code. These are the two rules a first-phase electric steelworks needs before it can sign a supply contract and specify its compensation. Both are within the regulator’s existing powers, both can build on texts that already exist (the MV tariff grid [S54][S03] and the connection code listed on the regulator’s website [S71]), and both would benefit every large user immediately.
In parallel, from 2027: the gas reserve audit. The audit is the precondition for everything else in gas, from firm power at Kribi to any direct-reduction plant. It takes time, so it should start as soon as possible after the FLNG’s departure, even though an electric steelworks’ first phase does not need gas.
By 2028: wheeling, balancing and certificates; the gas allocation framework. These rules matter for the second phase of an electric steelworks and for the first contracts between industrial users and new hydro or solar producers. They require more consultation, because they affect the utility’s revenue and the upstream partners’ economics.
Continuously: integrated planning of the Kribi zone. The demand register, capacity reservation and connection-charge policy should start with the commissioning of the 225 kV line at the end of 2026 [S14] and be updated every year.
None of these steps commits public money to a particular project. Each sets out how costs and risks are shared between the State, the utility, the transmission company, the gas sector and the users, which is precisely what investors and lenders need to see.
10.8 The milestones ahead
Figure 10.1 places these recommendations alongside the public milestones that are already scheduled and the indicative targets of RC-1.
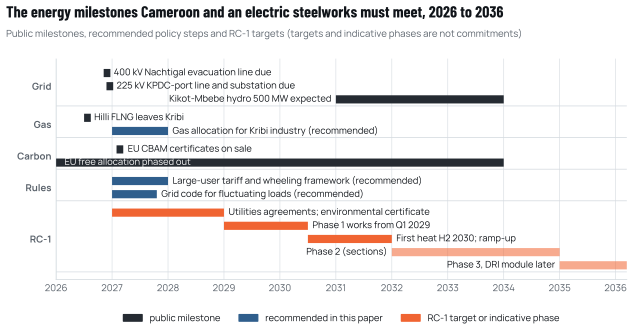
Source: Business in Cameroon, 9 October 2026 [S02]; PAK, 6 August 2025 [S14]; Kikot-Mbebe [S68]; FLNG departure [S16]; CBAM [S108][S109]; Cameroon Steel reference configuration RC-1 (planning estimate), indicative schedule [S07].
The sequence is favourable if the next two years are used well. The grid and port milestones fall at the end of 2026 and early 2027. The policy steps proposed here could be in place by 2028. Phase 1 of an electric steelworks is targeted to start works in the first quarter of 2029, after its environmental certificate, with a first heat in the second half of 2030 and ramp-up in 2031 [S07]. The European Union’s free allocation for its own steelmakers falls to zero by 2034 [S109], when low-carbon steel will be most valuable.
10.9 What large users can offer in return
Rules work best when obligations run both ways. In exchange for a published framework, an electric steelworks and other large users can offer the energy system:
- long-term, high-load-factor demand that improves the utilisation of new transmission and generation;
- investment in their own compensation and dedicated assets, so that the shared network is not burdened by their disturbances;
- schedulable load, through melting timed around the system peak and scheduled maintenance, worth about 1.6% to 2.3% of the national peak for a single plant of RC-1’s first phase (Chapter 9);
- anchor offtake for new hydro, through long-term contracts that improve the bankability of projects such as Kikot-Mbebe;
- transparency, through shared power-quality data and published energy and emissions indicators.
Other sources cited in the English text
- S10Carbon intensity of electricity generation (Ember data). Our World in Data, Dataset accessed Oct 2026.ourworldindata.org/grapher/carbon-intensity-electricity
- S05Données pétrolières 2025. SNH, posted Jun 2026.snh.cm/wp-content/uploads/2026/06/Donnees-petrolieres-2025.pdf
- S66Cameroon: Energy (Country Commercial Guide). US International Trade Administration, 13 Apr 2026.trade.gov/country-commercial-guides/cameroon-energy
- S01Rapport d’activités 2025 de l’ARSEL. ARSEL (electricity regulator), 7 Sep 2026.arsel-cm.org/wp-content/uploads/2026/09/Rapport-ARSEL-2025.pdf
- S44Hausse des tarifs d’électricité: l’ARSEL minimise l’impact sur les entreprises. EcoMatin, 6 Jan 2023.ecomatin.net/hausse-des-tarifs-delectricite-larsel-minimise-limpact-de…
- S45Électricité: les aciéries s’insurgent contre la hausse des tarifs. EcoMatin, 10 Jan 2023.ecomatin.net/electricite-les-acieries-sinsurgent-contre-la-hausse-des-…
- S54Décision N°00000427 fixant les tarifs de vente HT d’électricité des clients MT et seuils minima de négociation "Grands Comptes". ARSEL, 12 Dec 2022.arsel-cm.org/wp-content/uploads/2025/12/2022_decision_n_00000427_d_ars…
- S03Tableaux tarifaires, Décision ARSEL N°00000427 (MT 2023-2025). ARSEL, uploaded Jan 2026.arsel-cm.org/wp-content/uploads/2026/01/TABLEAUX-TARIFAIRES-decision-M…
- S04Décision fixant le montant de la RMA ENEO au titre de l’exercice 2025 (réajustée). ARSEL, 19 Dec 2025.arsel-cm.org/wp-content/uploads/2026/01/Decision-fixant-le-Montant-de-…
- S71Regulatory texts listed on the regulator’s website: orders on the connection code and the market code (files could not be opened on the access date). ARSEL.arsel-cm.org
- S13IEC TR 61000-3-7:2008, Electromagnetic compatibility, Part 3-7: Assessment of emission limits for the connection of fluctuating installations to MV, HV and EHV power systems (Ed. 2.0); indicative planning levels for flicker: Table 2 (section 4.2.1). International Electrotechnical Commission (table title read in the preview on the VDE Verlag site; values checked against secondary reproductions), 2008.vde-verlag.de/iec-normen/preview-pdf/info_iectr61000-3-7{ed2.0}en.pdf
- S73IEEE Std 519-2022, IEEE Standard for Harmonic Control in Electric Power Systems. IEEE, 2022.standards.ieee.org/ieee/519/10677/
- S42Prometal, Acero Metal, Aciéries du Cameroun… qui est le plus gros consommateur d’électricité de la métallurgie camerounaise. EcoMatin, 15 Jul 2026.ecomatin.net/prometal-acero-metal-acieries-du-cameroun-qui-est-le-plus…
- S17Cameroon’s SNH eyes Yoyo-Yolanda and new exploration blocks to sustain gas growth. Business in Cameroon, 6 Jul 2026.businessincameroon.com/energy/0607-16422-cameroon-s-snh-eyes-yoyo-yola…
- S84Golar signs Heads of Agreement for the development of a Floating Liquefaction export project in Cameroon (news release, filed with the US Securities and Exchange Commission on Form 6-K). Golar LNG Ltd, 24 Dec 2014.sec.gov/Archives/edgar/data/0001207179/000117184314006037/newsrelease.…
- S87Industrial gas: Cameroon suspends GDC’s 20% price hiking plan. Business in Cameroon, 18 Jul 2023.businessincameroon.com/energy/1807-13291-industrial-gas-cameroon-suspe…
- S52Reforming Cameroon’s power sector (on Law No. 2011/022 of 14 December 2011). IFLR (Orrick Herrington & Sutcliffe; ENEO), 3 Jun 2016.iflr.com/article/2gjw2n5ocpr2orkj9qxcr/iflr1000/reforming-cameroons-po…
- S53Tarif transport et GRT (Décision 0000017D). ARSEL, 17 Jan 2025.arsel-cm.org/wp-content/uploads/2026/01/TARIF-TRANSPORT-ET-GRT-1.pdf
- S21Kribi Power Development Corporation. MIGA (World Bank Group), 2014.miga.org/project/kribi-power-development-corporation-0
- S22The AfDB praises the impacts of the planned extension of the Kribi gas-fired power plant. Business in Cameroon, 1 Jul 2020.businessincameroon.com/energy/0107-10486-the-afdb-praises-the-impacts-…
本章引用的资料来源
方括号内的标记对应以下来源(按原文语言列出),完整列表见附录。 完整来源列表
- S109Directive (EU) 2023/959 (EU ETS revision). EUR-Lex (OJ L 130),2023年5月16日.eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX:32023L0959
- S02Nachtigal power line delays leave 150 MW of industrial demand unmet. Business in Cameroon,2026年10月9日.businessincameroon.com/public-management/0910-16939-nachtigal-power-li…
- S14Kribi franchit la ligne électrique 225 kV. PAK,2025年8月6日.按标题和日期引用
- S68Government, EDF push to deliver hydro promises as Cameroon moves to diversify energy sources. Business in Cameroon,2025年12月4日.businessincameroon.com/energy/0412-15443-government-edf-push-to-delive…
- S16Le navire usine quitte le Cameroun, le gaz s’arrête. Camer.be,2026年7月9日.camer.be/93911/12:1/le-navire-usine-quitte-le-cameroun-le-gaz-sarrete-…
- S108EU adopts CBAM Omnibus Regulation. EY,2025年10月22日.ey.com/en_gl/technical/tax-alerts/eu-adopts-cbam-omnibus-regulation
- S07Cameroon Steel reference configuration RC-1 (planning estimate), edition 10 October 2026 (RC-1.1): phases, benchmarks with ranges, indicative balances and schedule. Cameroon Steel,2026年10月10日.按标题和日期引用
引用本章
Cameroon Steel(2026)。喀麦隆水电主导的电网可为低碳钢铁供电,前提是大用户获得稳定供电、明确电价和天然气(中文摘要版)。白皮书05,第10章:五项规则而非补贴,可使喀麦隆能源体系为重工业做好准备。CS-WP-05。https://www.cameroon-steel.com/zh/library/energy-for-industry/policy-recommendations/
来源